01 Fintech / Mobile wallet 2021
UOBAM Robo-Invest on Singtel Dash
Making investing part of an everyday wallet.
Singtel Dash, a Singapore mobile wallet, partnered with UOB Asset Management (UOBAM) to offer robo-advisory investing. The hard part was fitting a regulated sign-up, with eligibility, identity and tax checks, into a wallet people used for everyday payments. We built one journey from the first risk question to the first deposit, with the exceptions mapped before the screens were drawn.
Discovery
Mapping the constraints first.
Singtel partnered with UOBAM to offer investing within the Dash mobile wallet, adapting UOBAM’s existing investment product for Dash users. With over 1 million registered users by December 2020, Dash was among the largest non-bank mobile wallets in Singapore, and the mutual goal was to get more users and revenue. There was no time for formal research, so before we started I ran guerrilla interviews with foreign domestic workers, who were one of Dash’s primary user groups and used it to send money home. Those conversations shaped my working assumption that familiarity with the mobile wallet wouldn’t mean confidence with investing.
What I heard.
- Trust over returns. Most sent money home with Dash, and chose Singtel because they trusted a national brand more than cheaper fees. So the design needed to always show where the money is and what happens next.
- Do more with the money that’s there. Some preferred Dash to a bank, with no queues or passbooks, and some employers paid them straight into Dash. So investing needed as few extra steps as possible.
- Don’t assume confidence. They preferred saving to investing. So risk had to be asked about first, and explained plainly.
- Make small and regular easy. Those who would invest would start small, and a monthly plan would work. So each funding method shows its minimum before the amount, and a recurring deposit is a single toggle.
One map to review together.
After being briefed by Dash’s product manager, Wai Kean, and the UOBAM team, I mapped the required checks, branches and exception states as one journey before drawing any screens, and we reviewed where an application could continue or had to stop. The map gave everyone one picture to review. Two gates needed explicit branches: US-person status decided whether an application could continue, and Singpass MyInfo or manual registration decided how identity details were collected. These checks were part of the onboarding requirements supplied by UOBAM. The exercise also showed that the risk assessment needed to move up front.
01 / Eligibility
Who can continue?
US-person status is a gate. An ineligible applicant does not enter the next stage.
Before you start
Read the disclosures
Product information, risks and consent.
Eligibility
US-person status
Check eligibility
Establish eligibility and current US-person status.
Currently a US person?
Yes: not eligible, end the flow. No: continue to risk assessment.Yes / End flow
Not eligible
Show the eligibility explanation. The application stops here.
Risk questionnaire
Continue to risk assessment
Assess risk, then confirm a portfolio before KYC.
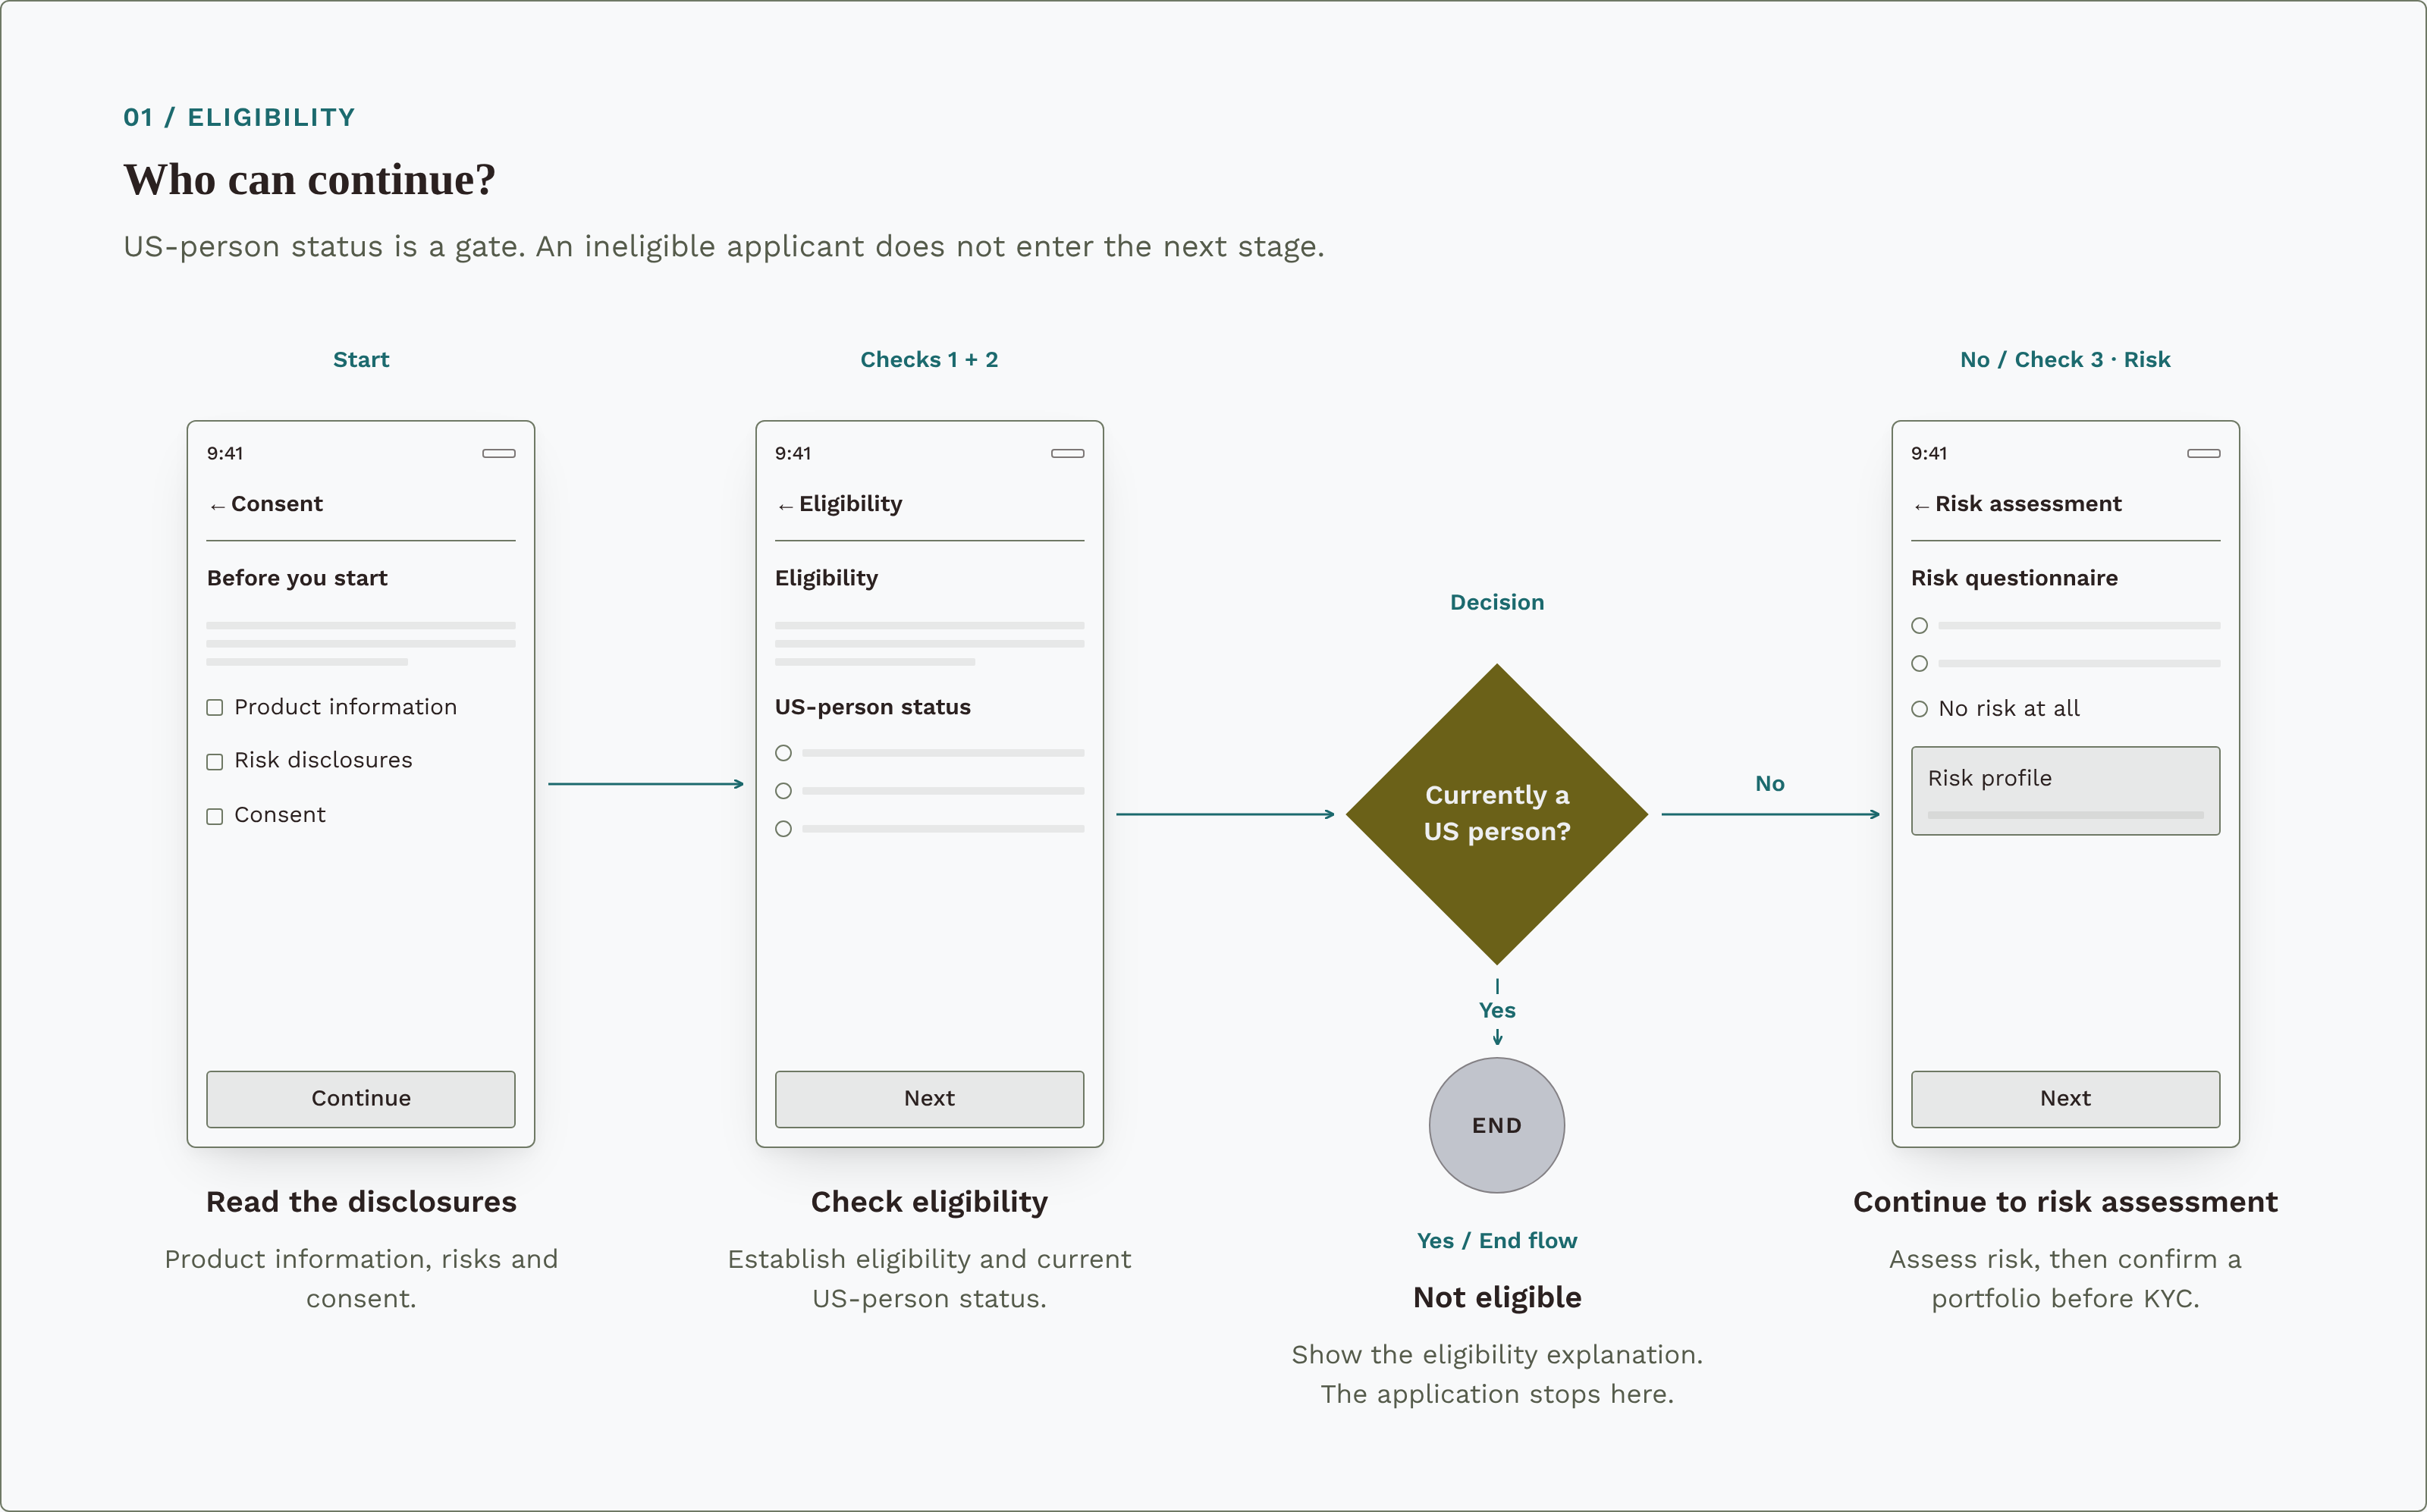
Diagram preview
02 / Know your customer
Two ways to provide identity details.
MyInfo and manual registration converge on the same ID check before the remaining application details.
Use Singpass MyInfo?
Yes: review prefilled MyInfo details. No: register manually.Prefilled from MyInfo
Review prefilled details
Bring in the identity information already held in MyInfo.
Complete missing information
Keep the prefilled details, then add what is missing. Editing a prefilled detail shows a warning before switching to manual registration.
Identity documents
Enter identity details
Choose manual registration directly, or switch after the editing warning.
Review the form and documents
Complete the identity fields and required documents before continuing.
ID matches the Dash account?
Yes: continue to additional information and CRS. No: show a blocking mismatch alert and review the identity details.No / Progress blocked
Resolve the ID mismatch
Explain the mismatch. Dismissing the alert returns to the identity details; it does not submit the application.
Complete the remaining details
Employment, source of funds and CRS tax residency.
Review and declare
Declare and submit
Review the declaration and give consent to submit.
Application submitted
Verification follows
Submission begins verification; it does not mean the account is approved.
- Unchanged MyInfo
- Pending review
- Manual / edited MyInfo
- Pending video call
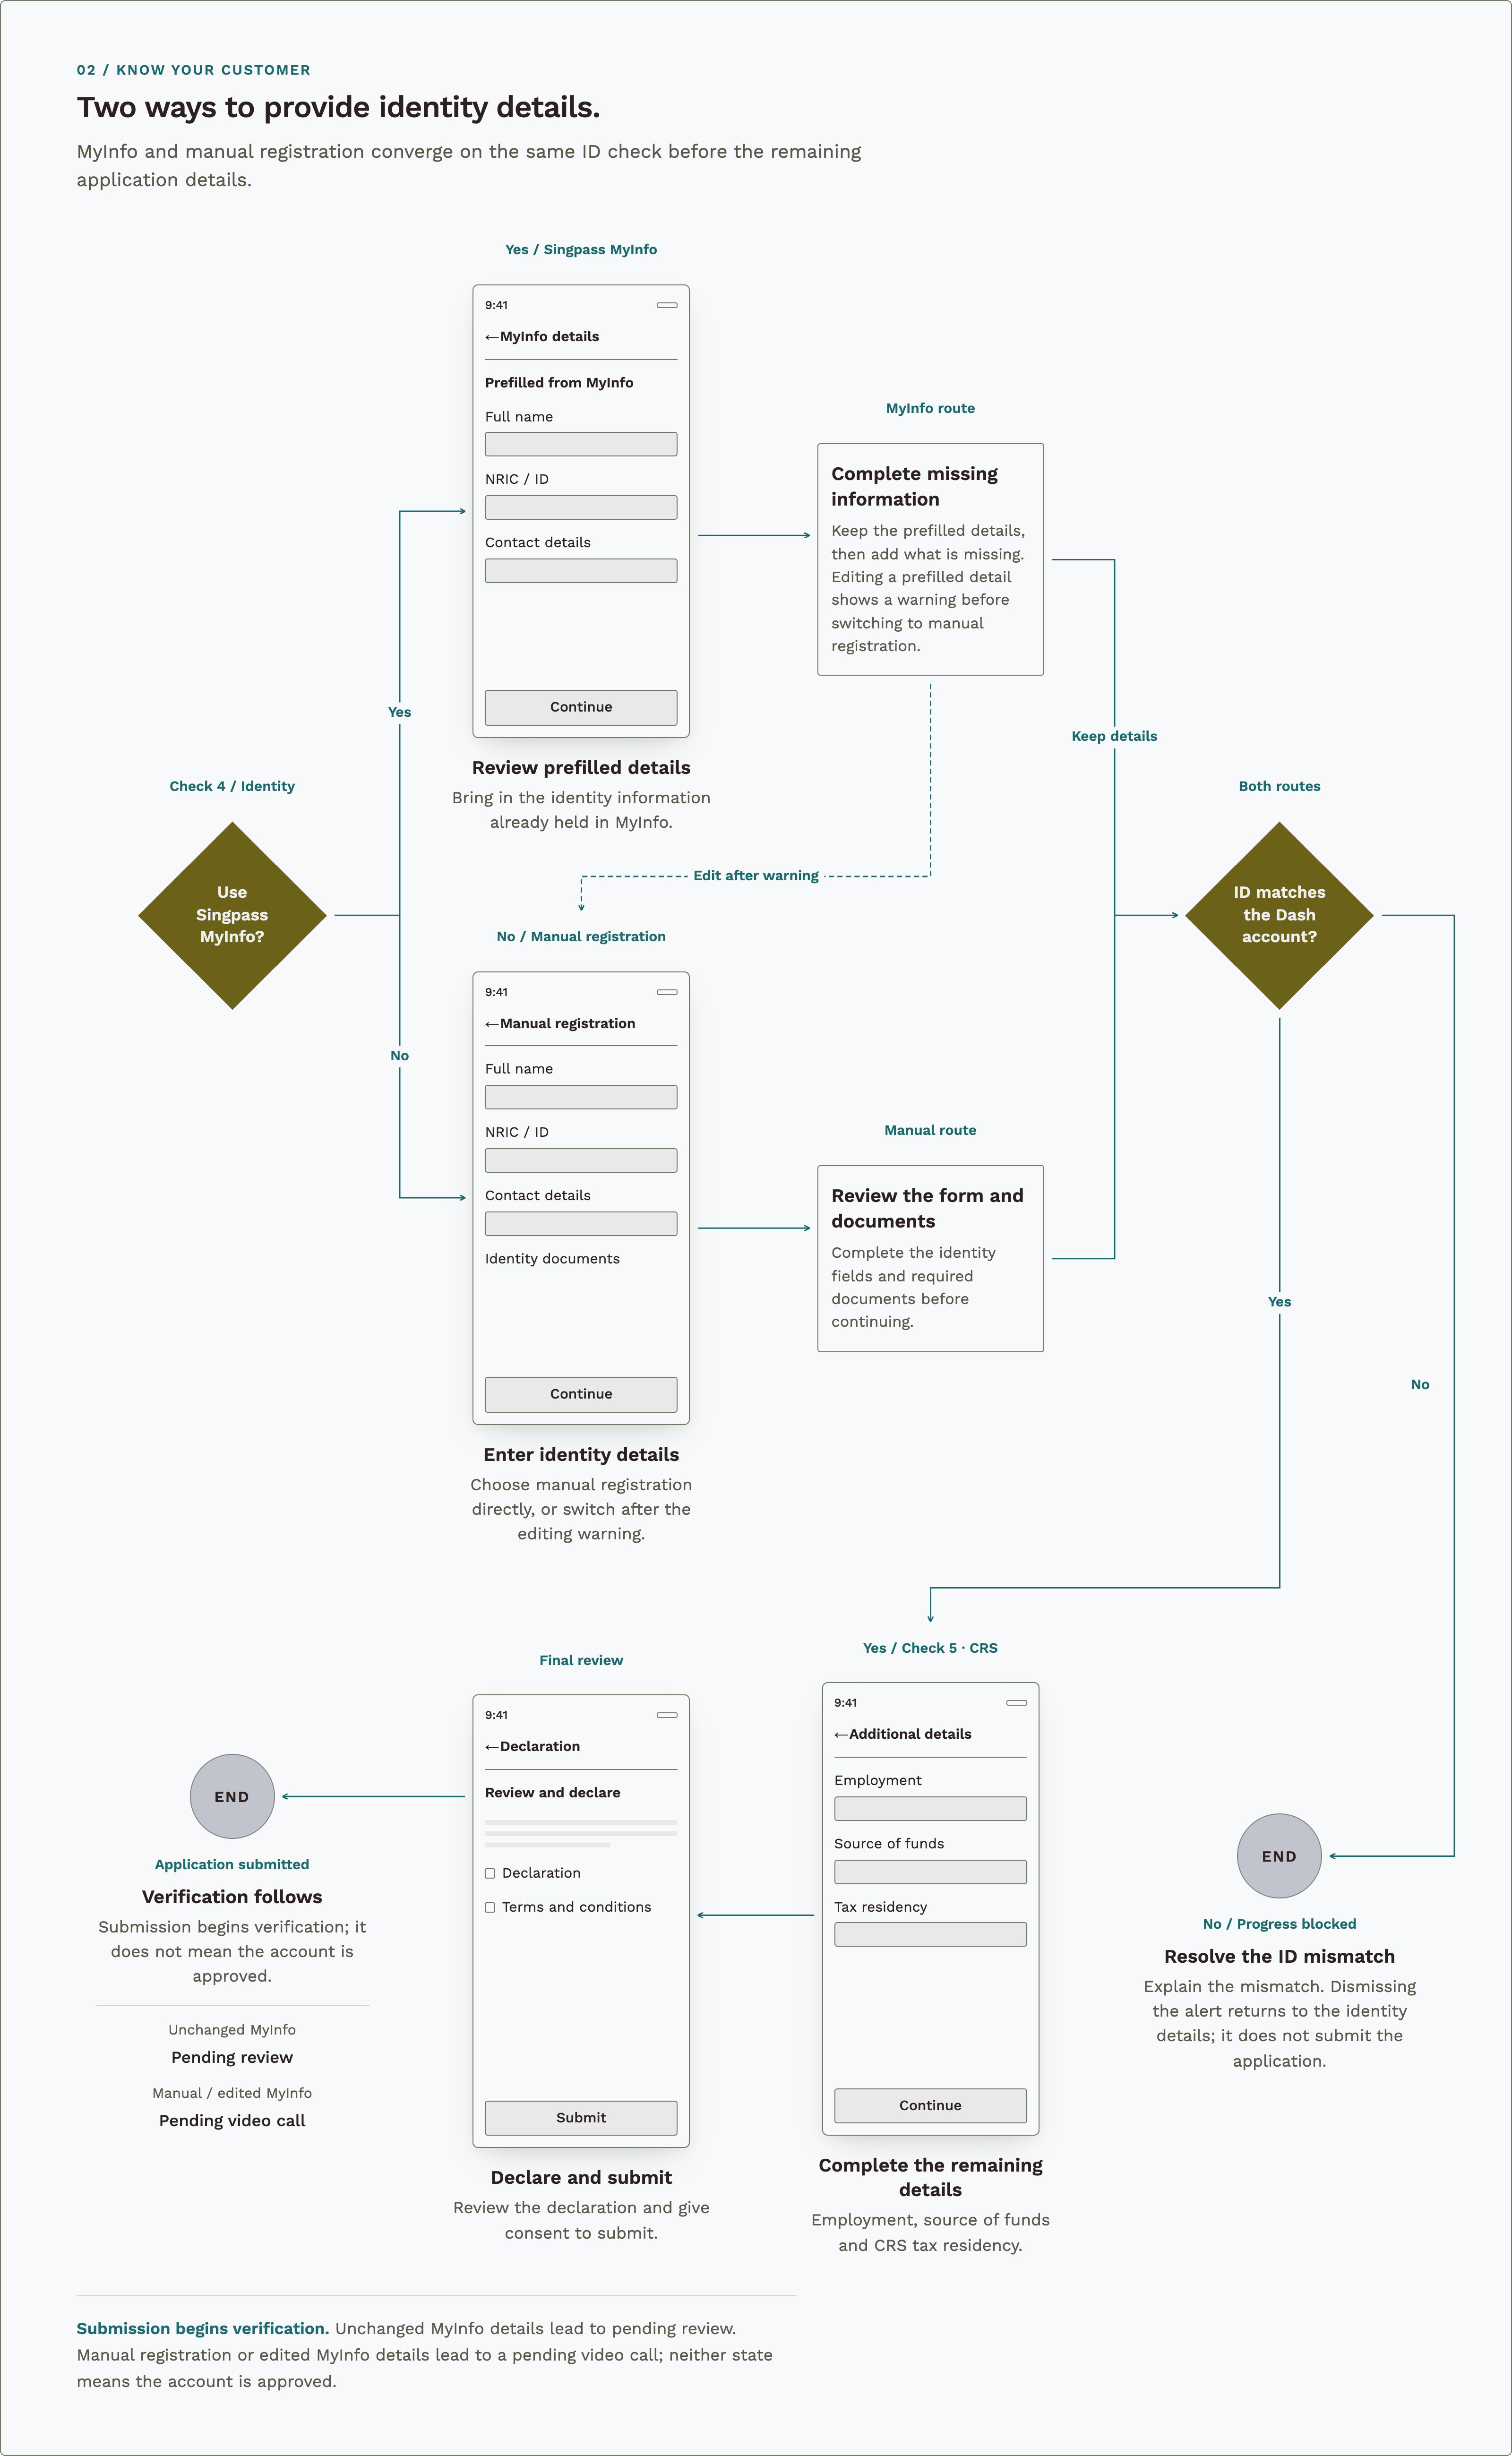
Diagram preview
Design
Where the money is, and what to do next.
The hardest decision throughout was what to share and what to hide. From earlier research, Dash’s primary users included foreign domestic workers sending money home, students without credit cards, and older customers looking for deals. I wasn’t sure which of these user groups would convert into UOBAM users but the assumption is that they wouldn’t have too much investment knowledge to begin with. So, too much information would confuse them, but not revealing necessary information would require them to go through too many hoops before they could make decisions.
Decision 1
Ask about risk first.
UOBAM’s original onboarding, from its existing app, started with planning: an introduction to the Portfolio Planner, a goal, a time frame and contributions. The first risk question was much later, at step 12. Someone who went through the effort of Singpass MyInfo and the KYC flow could end up not being able to invest if they chose “I do not want to take any risks”.
This would be a terrible experience. Nobody should hand over personal details for an answer that ends their application, so I moved the risk assessment to the start of onboarding, straight after the eligibility check, and made the first question a gate.
UOBAM’s order made sense in its own app, where the person signing up was a brand-new user and moving them further through registration was the goal. Dash’s users were existing customers, and we didn’t want to spoil an experience they already had just to push them further through a sign-up. The change was to the order, not to what UOBAM needed to collect, and it was agreed without pushback.
During internal testing, I proposed moving that answer to the top of the list. I recall UOBAM keeping it last to let clients continue, so the answers that led to investing came first. The way out was there, but less prominent. I accepted that: it was their product and their call, and the gate before personal details was already in. I’d have tested the wording and the order with people new to investing if I had more time.
Before / The original order
Risk came after the plan.
Goals and contributions came first. The first risk question was step 12, and choosing no risk only ended the application after KYC.
Three steps to your portfolio
Three steps
Goals and contributions, then risk and portfolio, then personal details.
Your goals
Meet the planner
Six introduction slides, then the Portfolio Planner.
Choose how you want to invest
Choose a goal
Build my wealth, retirement, a house or education, and how long for.
How long are you saving for?
Set contributions
A single contribution, a regular one or both.
Risk questionnaire
Assess risk
Every answer continues, including no risk at all.
Your plan
Plan the portfolio
Adjust goals, risk and contributions in the planner.
Complete KYC
MyInfo or manual registration, the ID check, employment, source of funds, CRS and the declaration.
Chose no risk / End flow
Not eligible
Only now is someone who wanted no risk told they can’t invest.
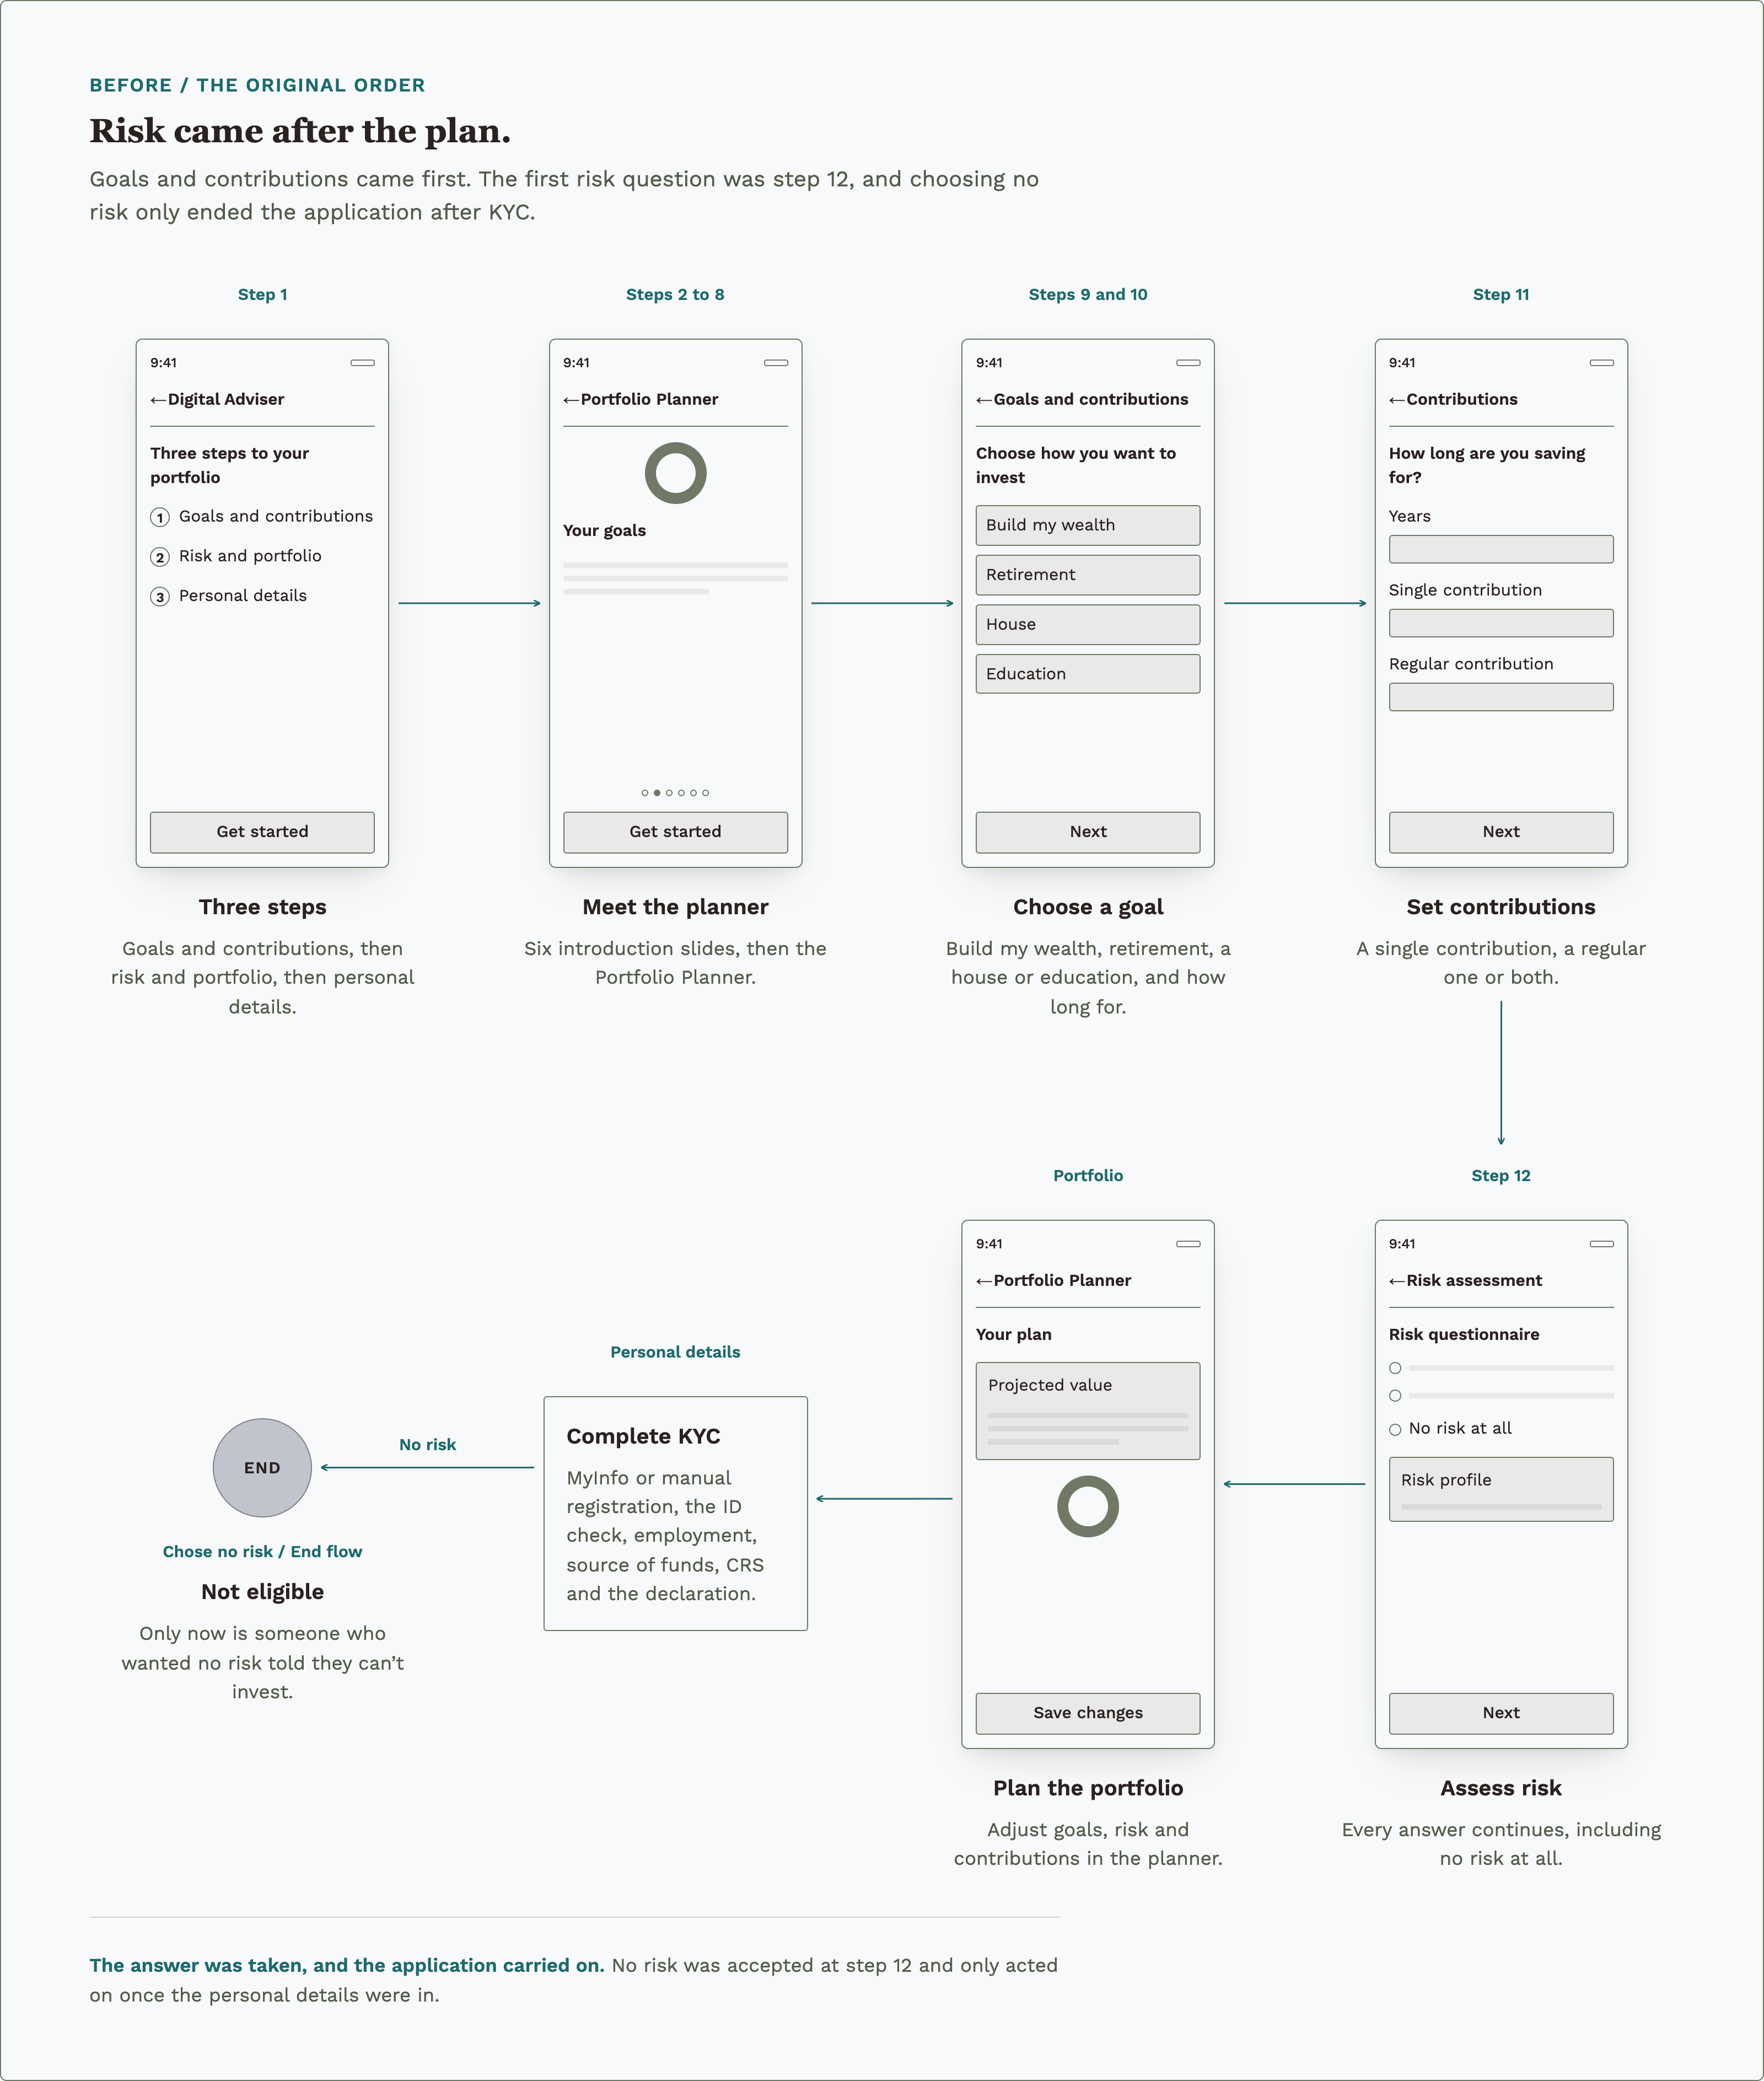
Diagram preview
After / Risk first
Risk comes first.
After the disclosures and eligibility check, onboarding opens on the risk questions. Choosing no risk is explained at the first one.
Your objectives
State your objectives
Nothing is pre-selected. The last answer is no risk at all.
Chose no risk?
Yes: explain why and point to UOBAM. No: continue to the second question.If your portfolio fell
React to a fall
What you would do if the portfolio lost value.
Retake
See your profile
Next to continue, or Retake to start the questions again.
Find out why
Every investment carries risk. Contact UOBAM, or Okay to go back.
Invest sustainably?
Choose ESG or not
Whether to consider sustainable funds.
Your recommendation
Change portfolio
Confirm a portfolio
One recommendation, with Change Portfolio close by.
Complete KYC
MyInfo or manual registration, as mapped in Discovery.
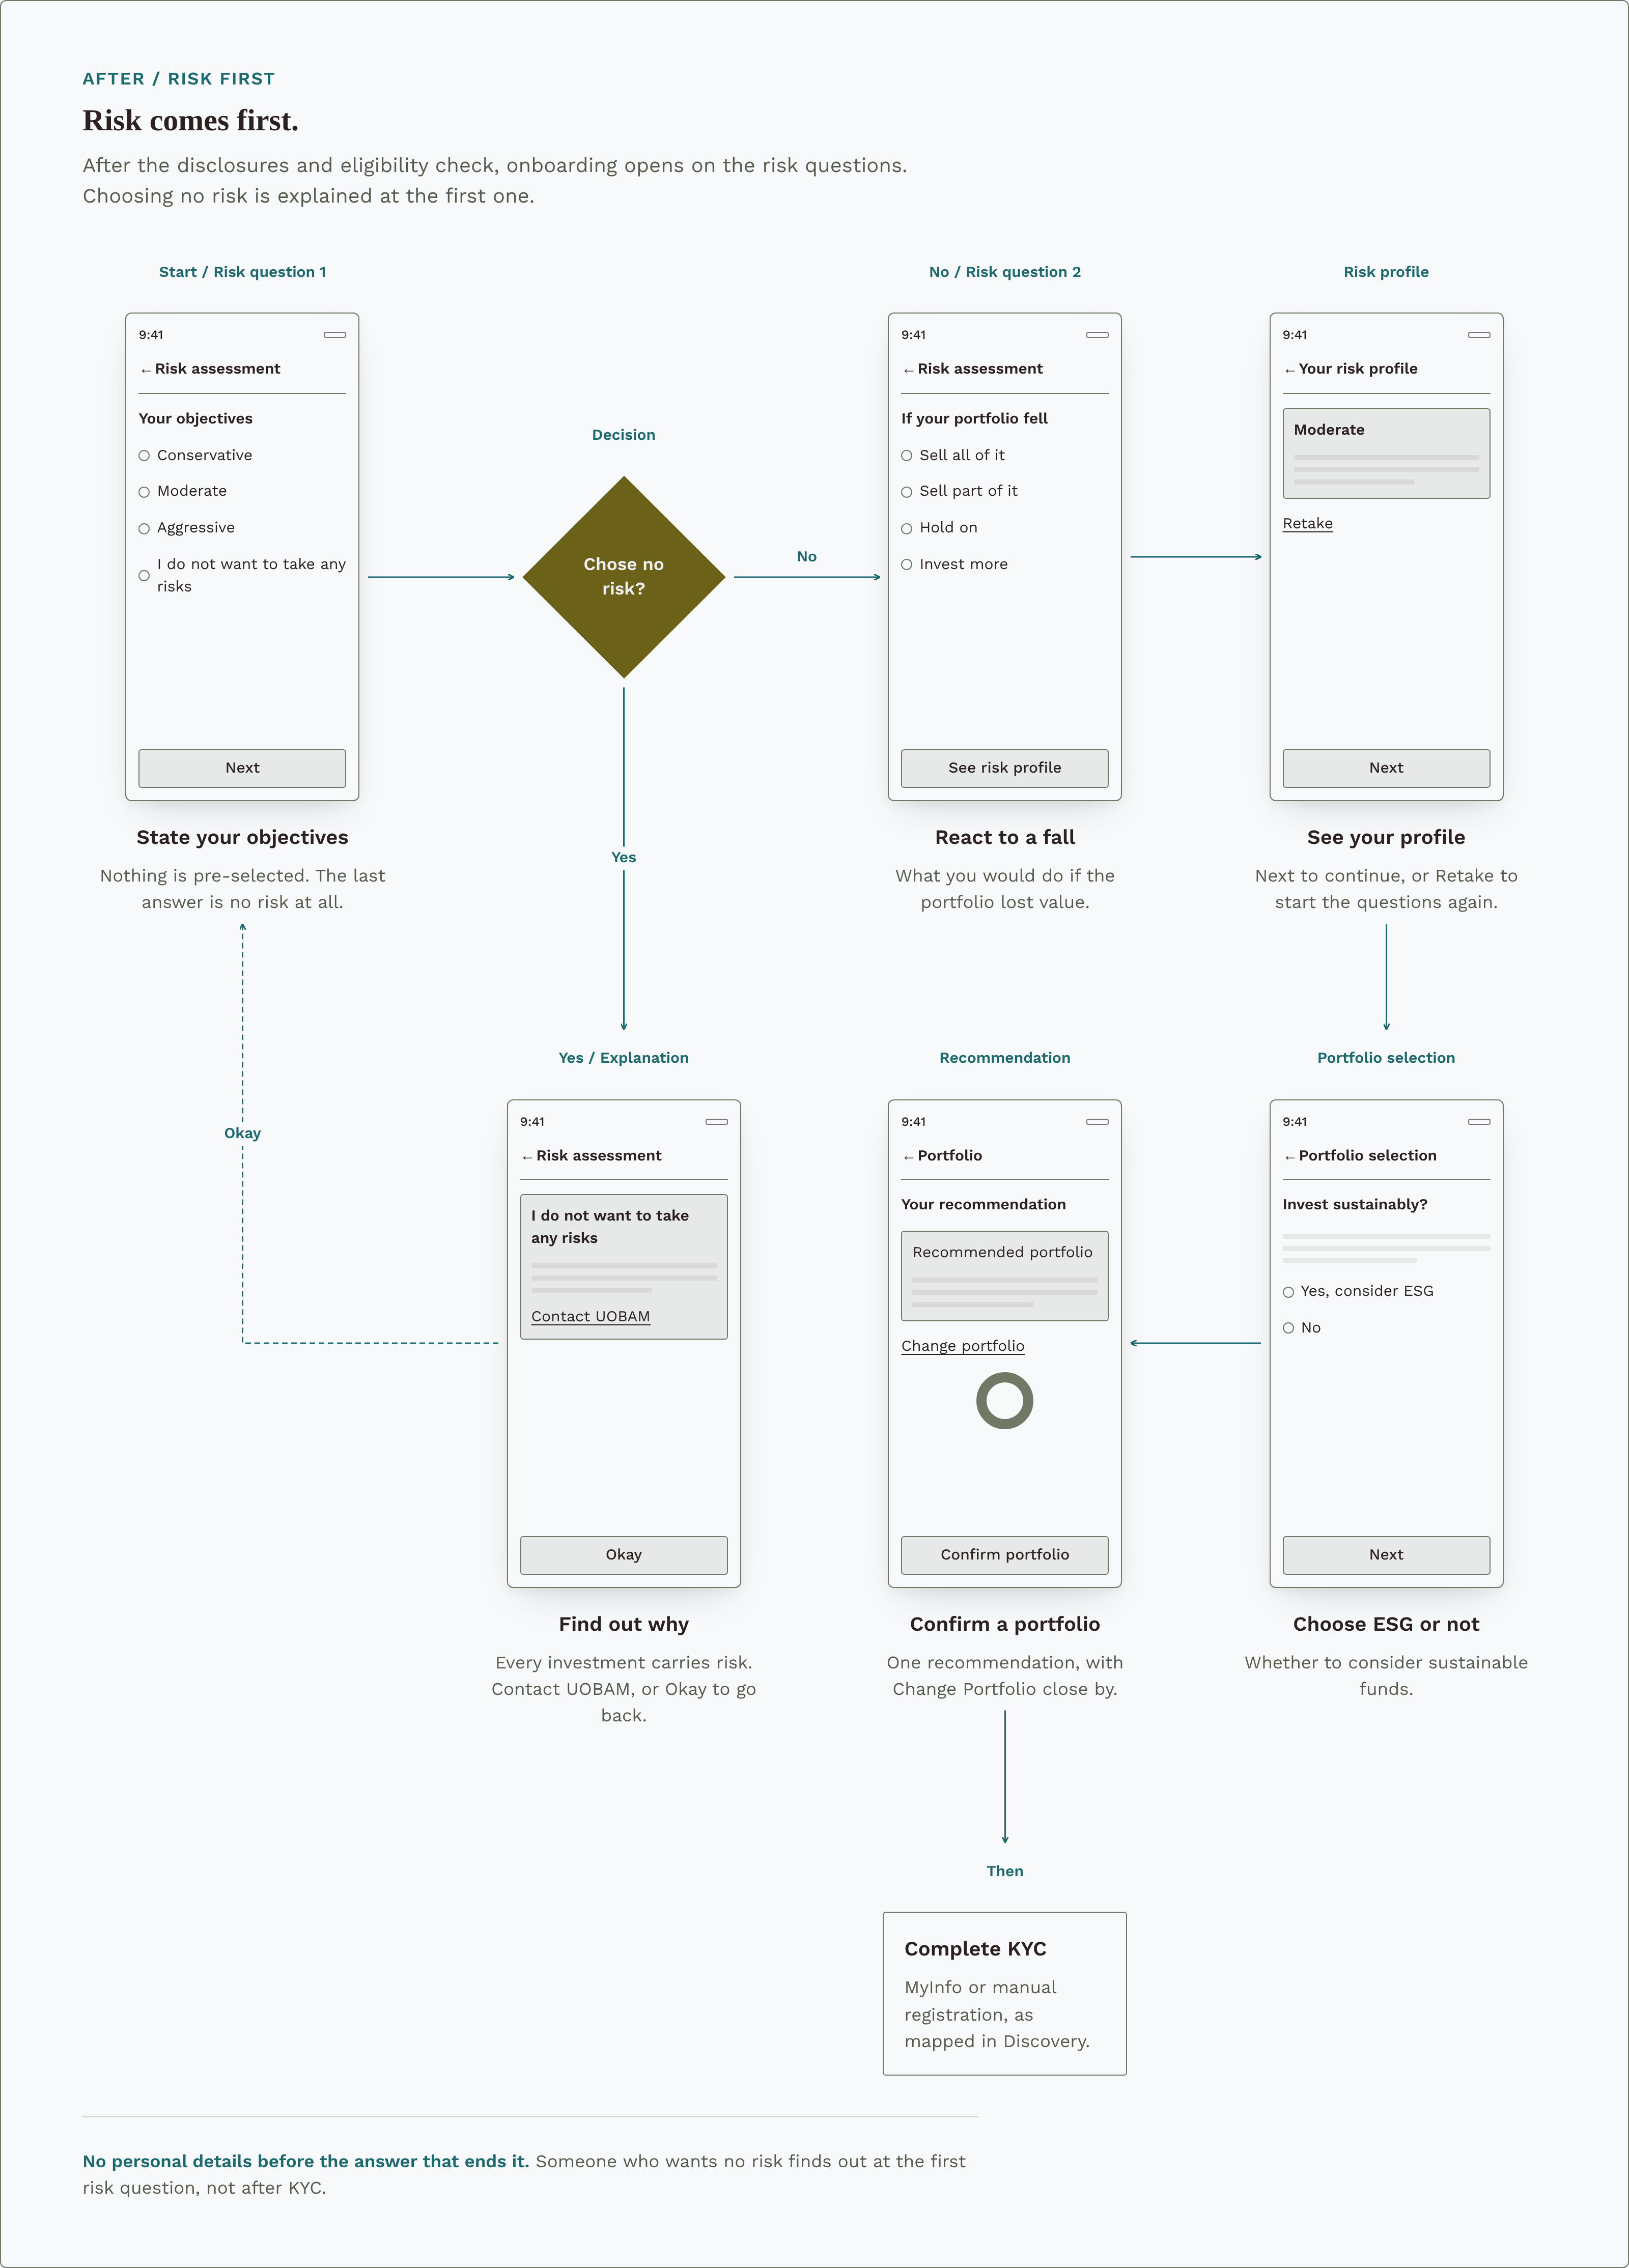
Diagram preview
Decision 2
Show people where their money is.
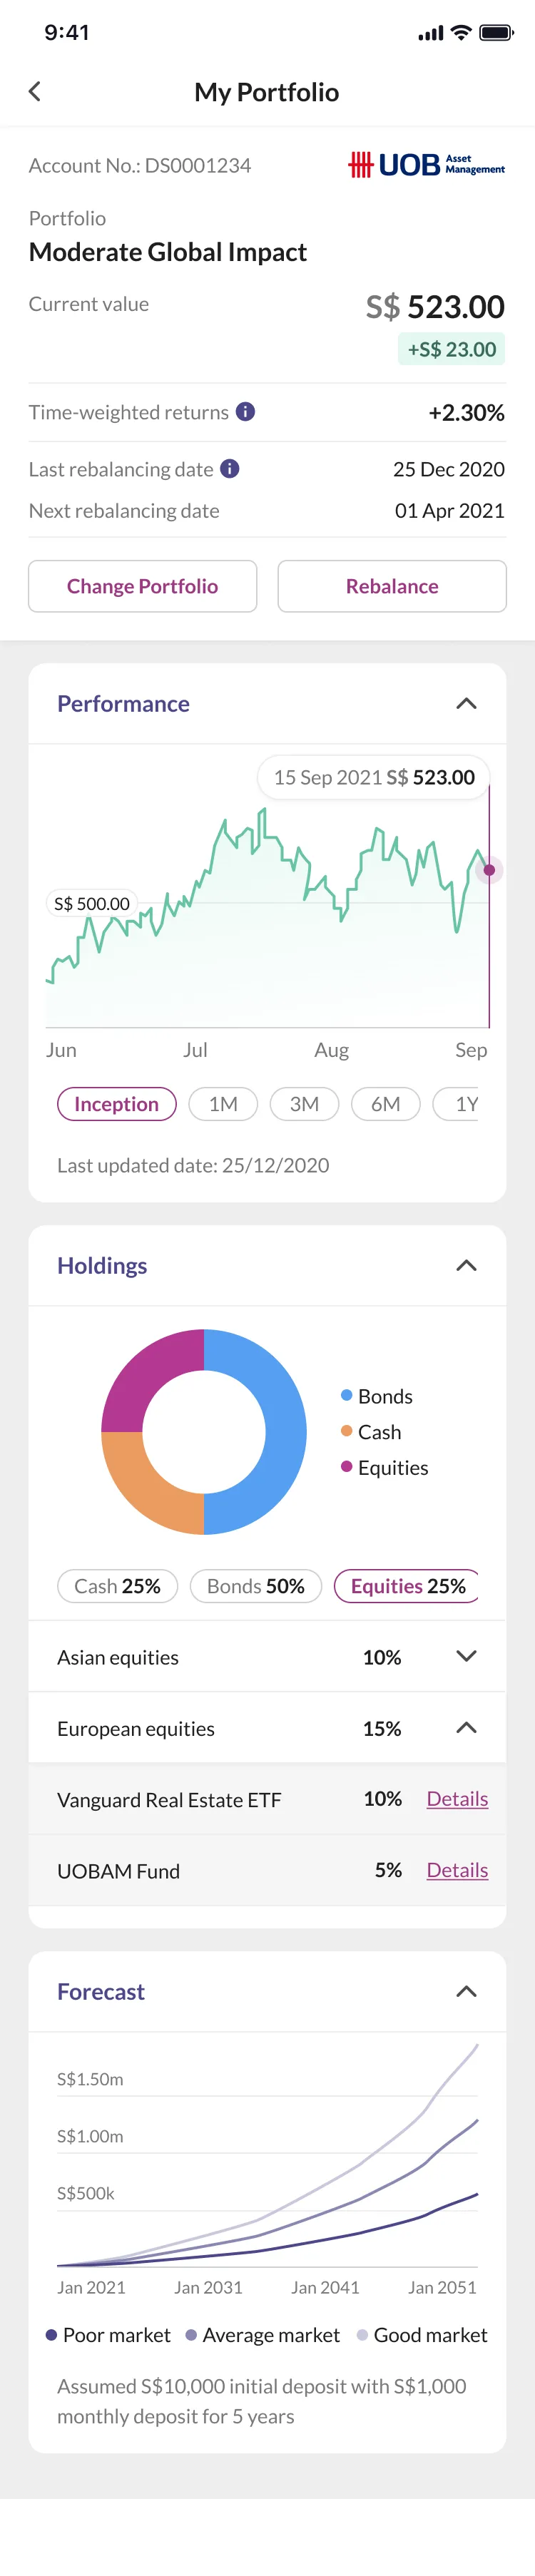
The portfolio needed to support a quick balance check as well as a closer look at the investment. I put current value, returns and the main actions first, with performance, holdings and forecasts in separate sections below. That kept the first read focused without removing the underlying detail.
The trade-off was a longer page, with some information behind expandable sections. I kept past performance separate from projections and retained the forecast assumptions, but I had not tested whether people understood that distinction.
Concepts for choosing a portfolio.
Before settling on the final design, I explored different ways to show risk, the forecast and the recommendation. Each one showed me something the final design needed to avoid. The final screens follow. All are low-fidelity wireframes with sample figures.
Choosing a risk level
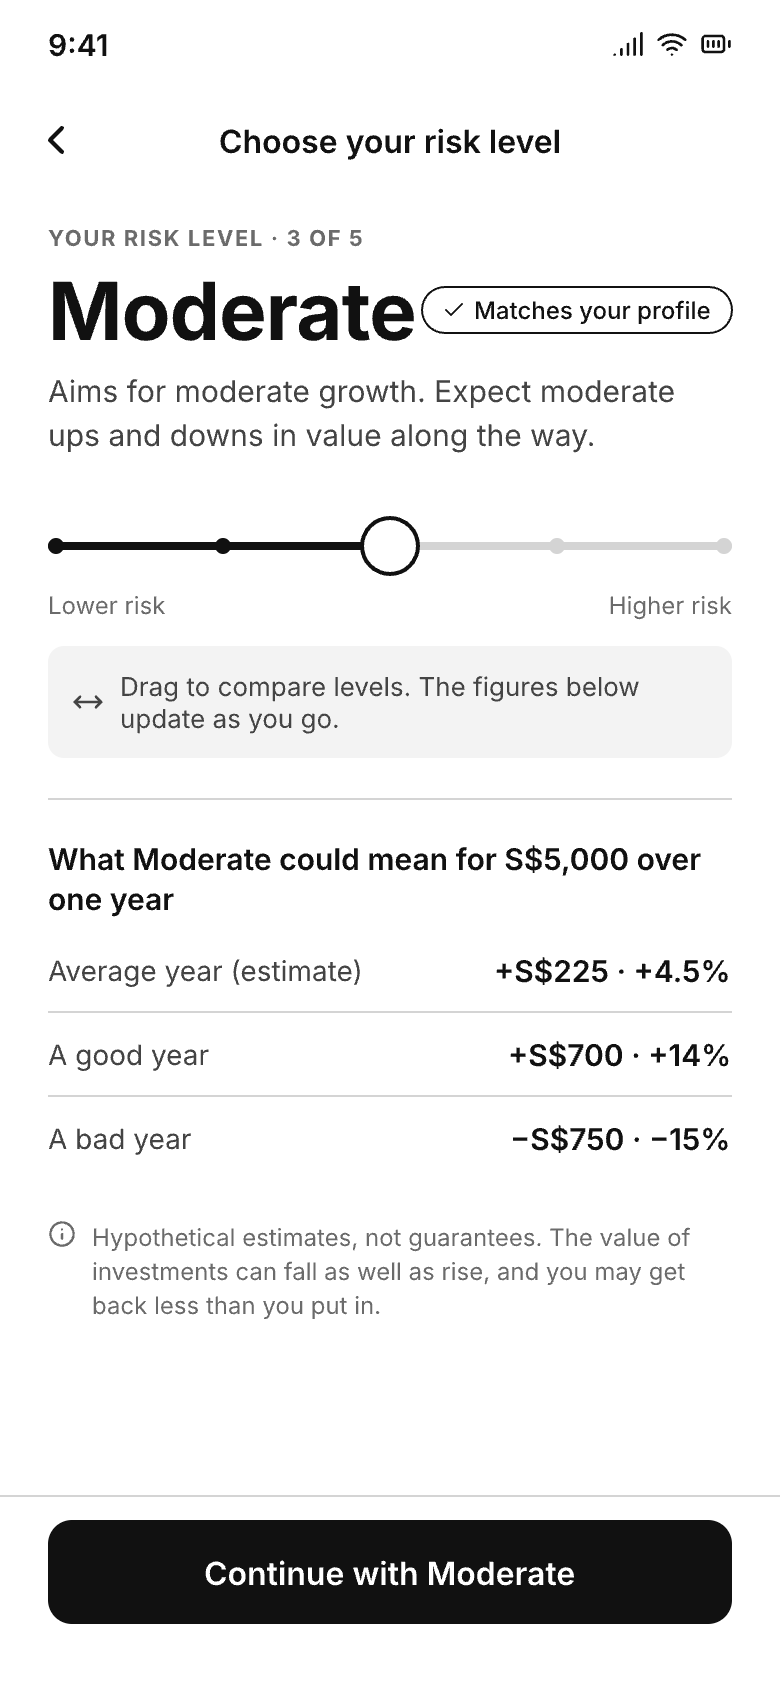
A name, not a number. Leading with the level’s name gave people a word to hold on to. It carried through to “Your risk profile” in the final design.
A decision before a recommendation. Opening on a slider asked beginners to pick a level before seeing what we’d suggest. The final design leads with the recommendation and keeps the slider in Change Portfolio.
Easy to watch the number go up. Three rows change with every drag, so the eye follows the gain and skims past the bad year at the bottom.
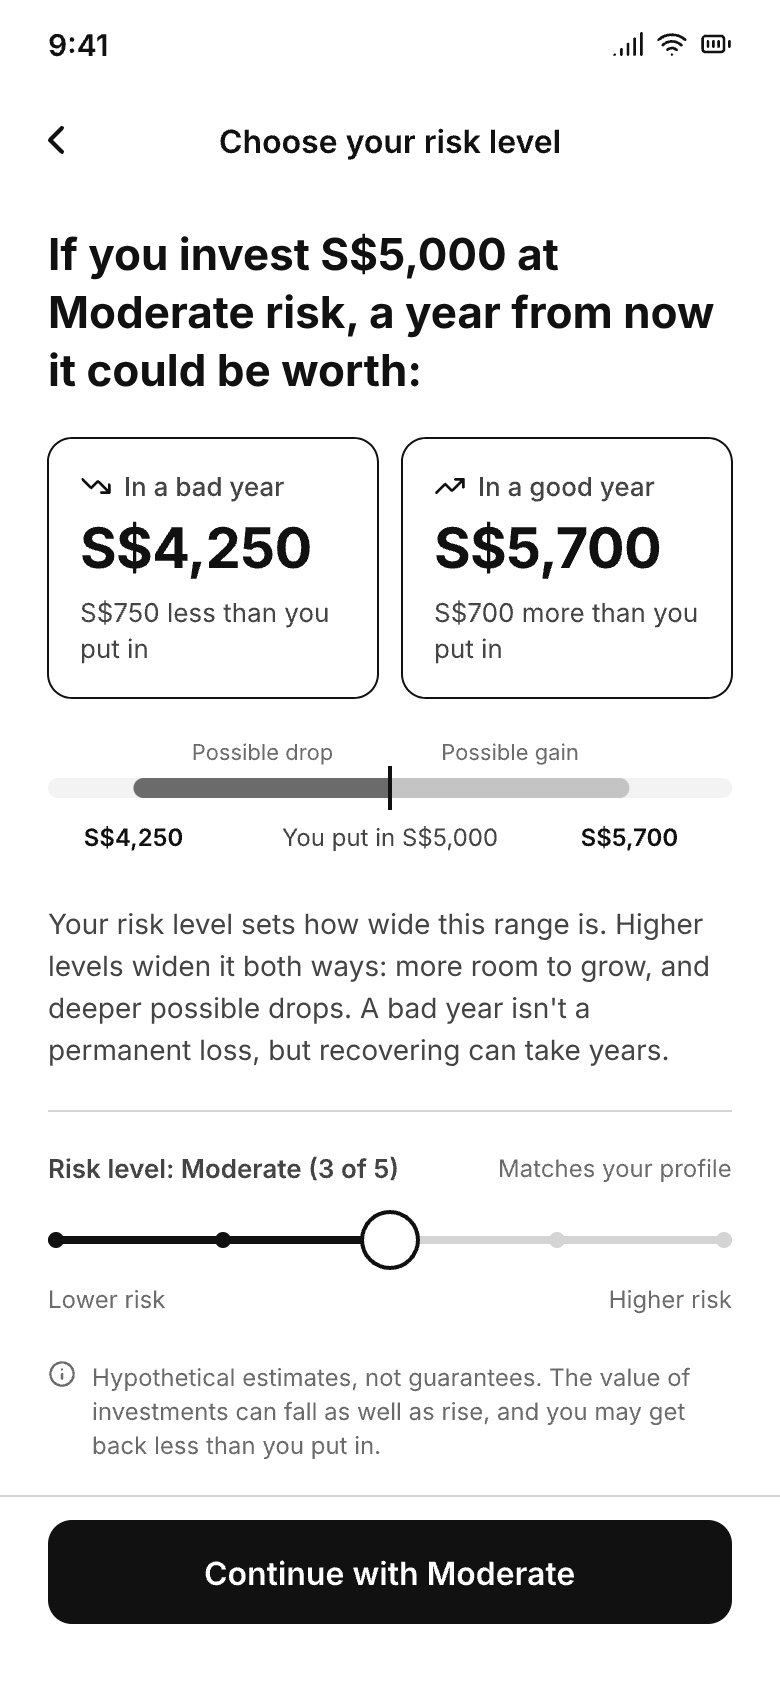
A loss as the opening line. A bad year in large type, before anyone had seen a portfolio, made the first step of investing read like a warning.
The same range, twice. The range bar repeats the two cards above it.
A paragraph to explain the picture. If the range needs four lines of explanation, the picture isn’t doing its job.
The control, demoted. Pushing the slider below the fold with a small label made changing your level feel discouraged.
Reading the forecast
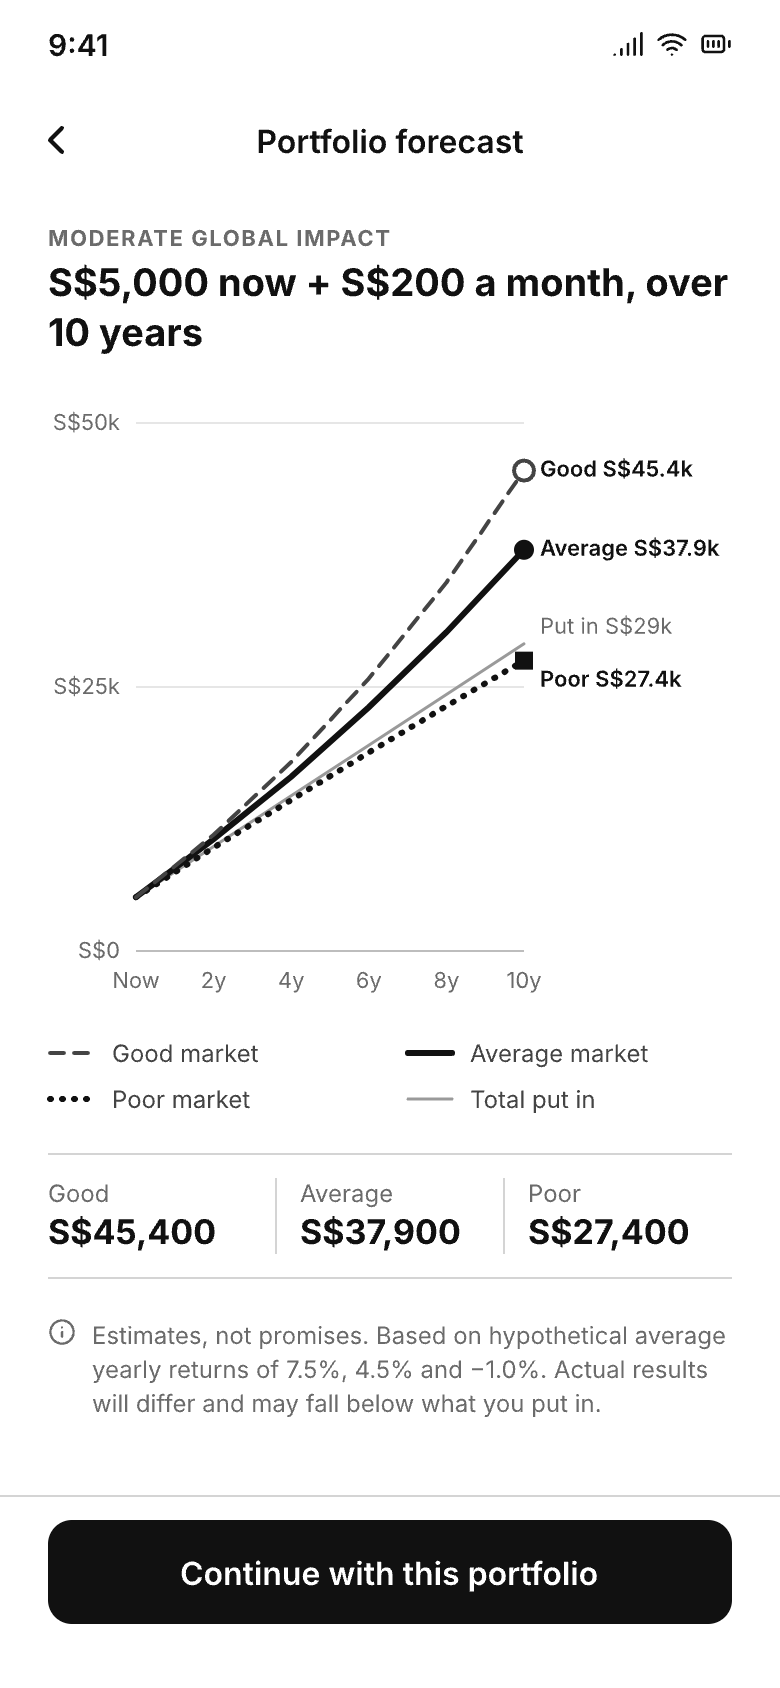
A forecast without the portfolio. The screen shows what the money could become, but not what it’s invested in. The final design puts expected returns and allocation first, with the forecast beneath.
Labels pile up at the line ends. On a phone-width chart, “Put in” and “Poor” crowd into the same corner.
The same numbers, twice. The values row repeats the end of each line, which doubles what the eye has to reconcile.
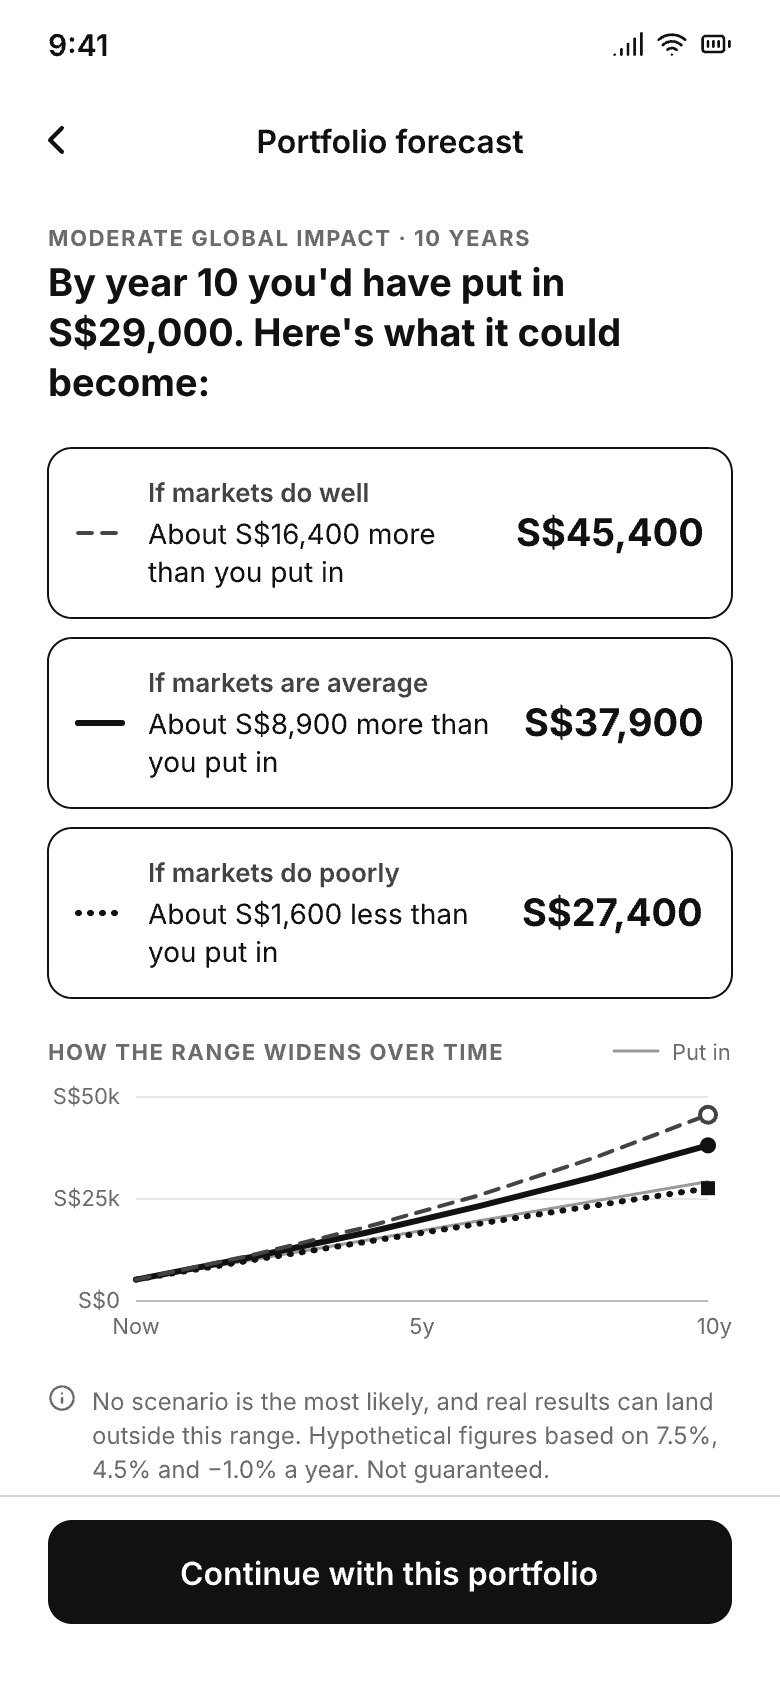
Tidy cards, false precision. Three boxed figures make a continuous range look like three outcomes to pick from.
Plain words, without approval. “About S$1,600 less than you put in” reads like a personal projection. As I recall, UOBAM owned the forecast wording and every disclaimer, and plain-language scenarios weren’t part of it.
The chart as an afterthought. Shrinking the chart to fit under the cards hid how the range widens over time, which is the point of a forecast.
Accepting a recommendation
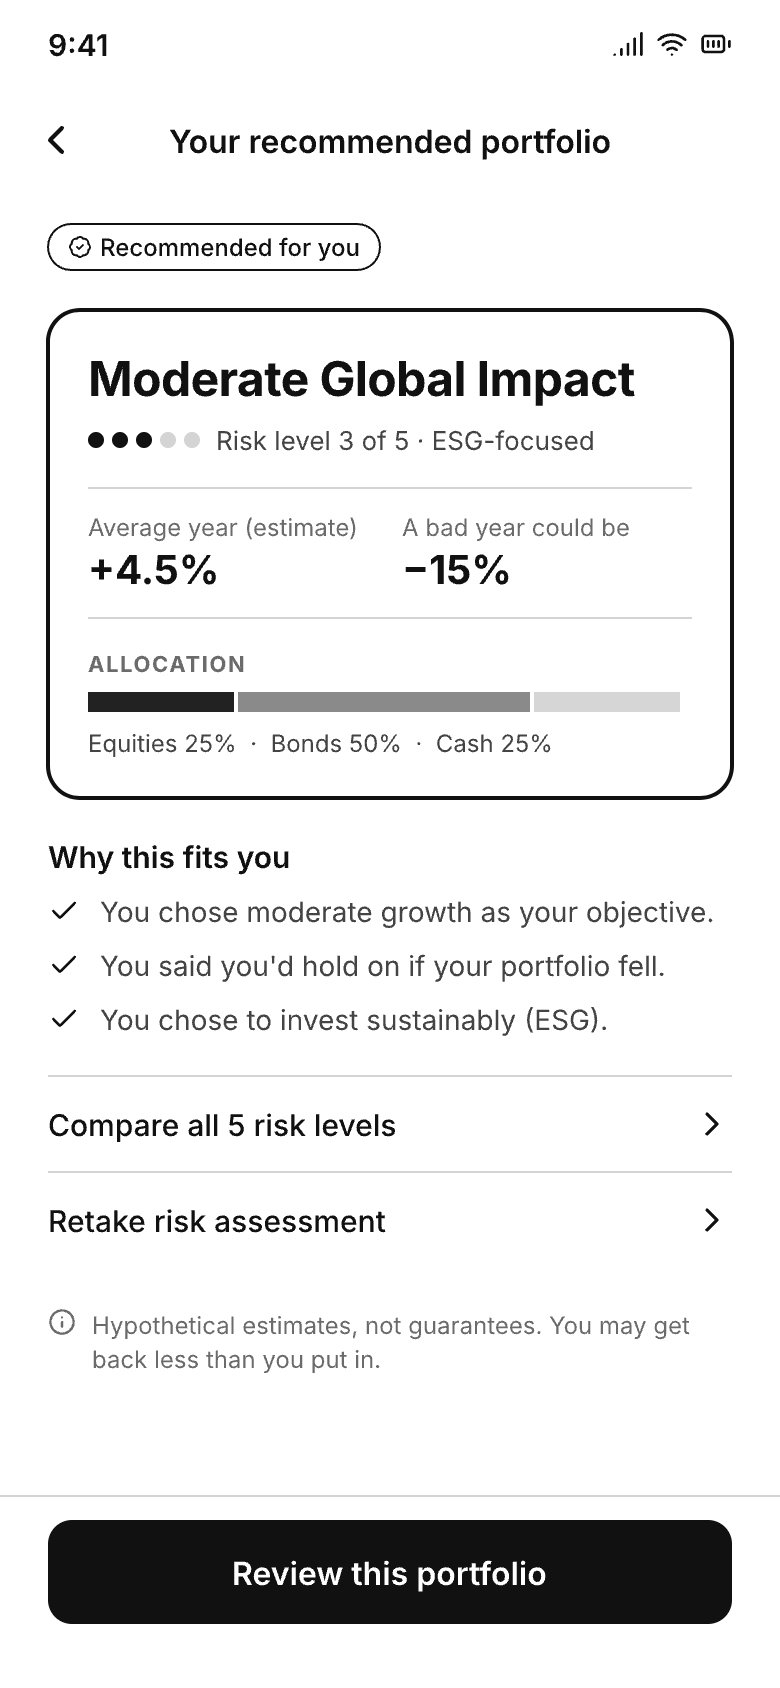
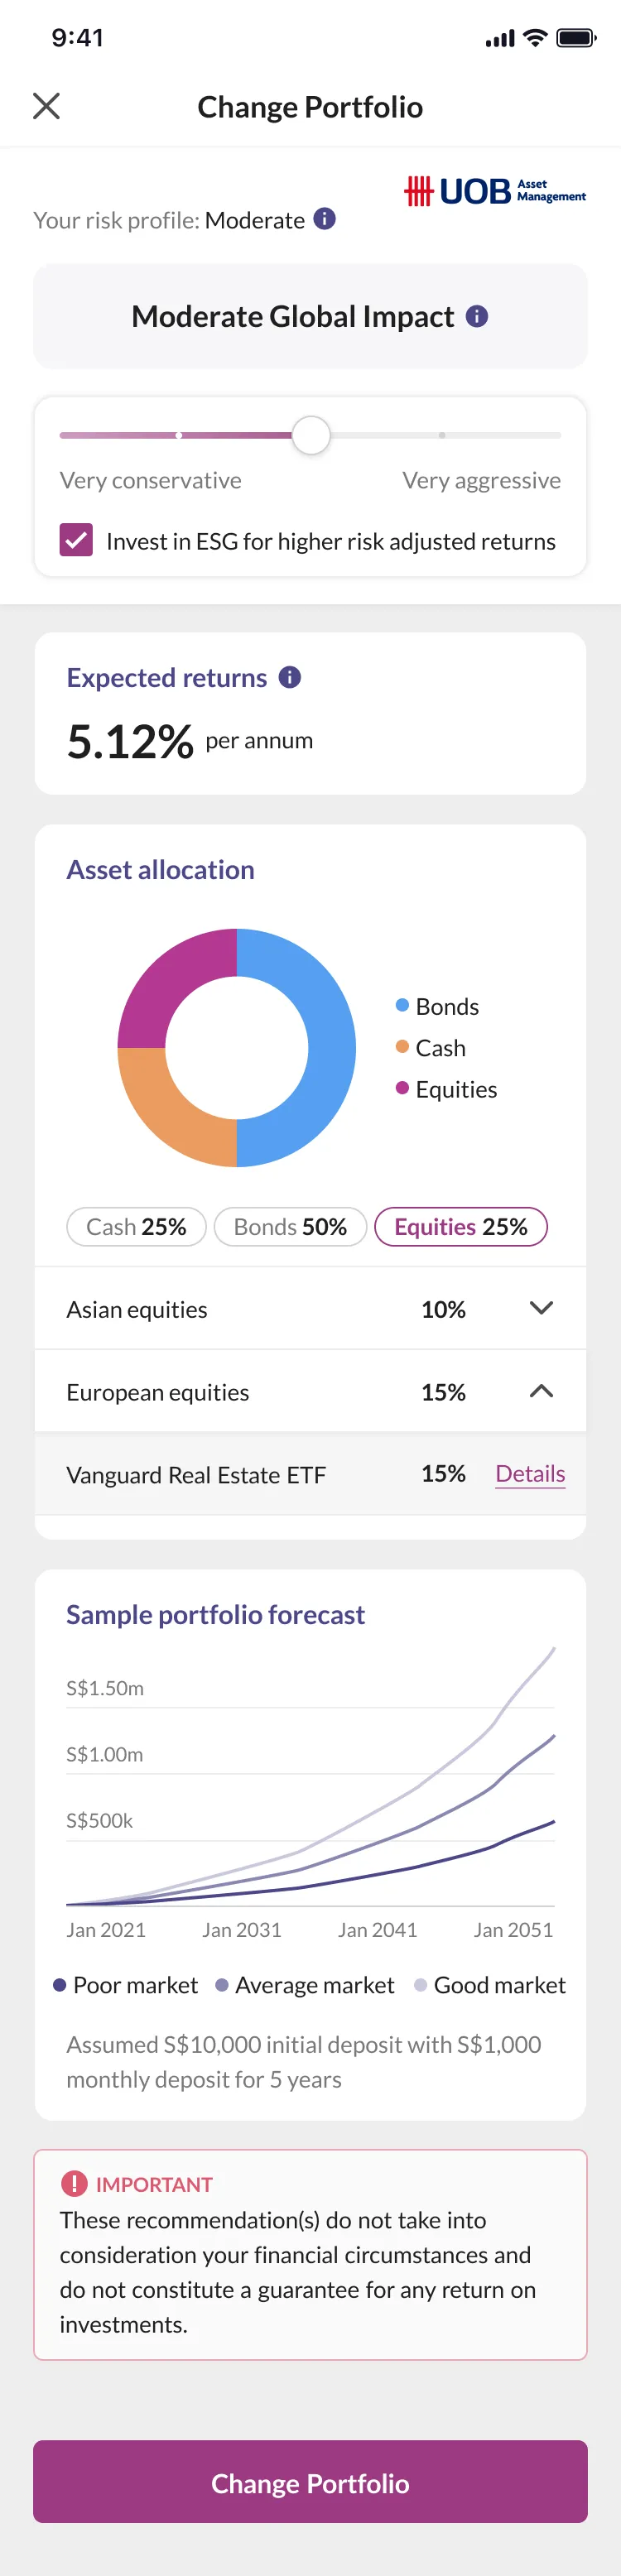
One clear recommendation. A single portfolio up front spares a beginner from comparing. The final design opens the same way.
No way into the funds. A single allocation bar says how much is in equities, not what you’d actually own. The final design lets people open each fund.
Two exits, equal weight. Comparing levels and retaking the assessment sit side by side, which invites people to retake the questions until they get the answer they want.
One more screen. “Review this portfolio” sends people elsewhere before they can confirm. The final design keeps the details and Confirm Portfolio on one page.
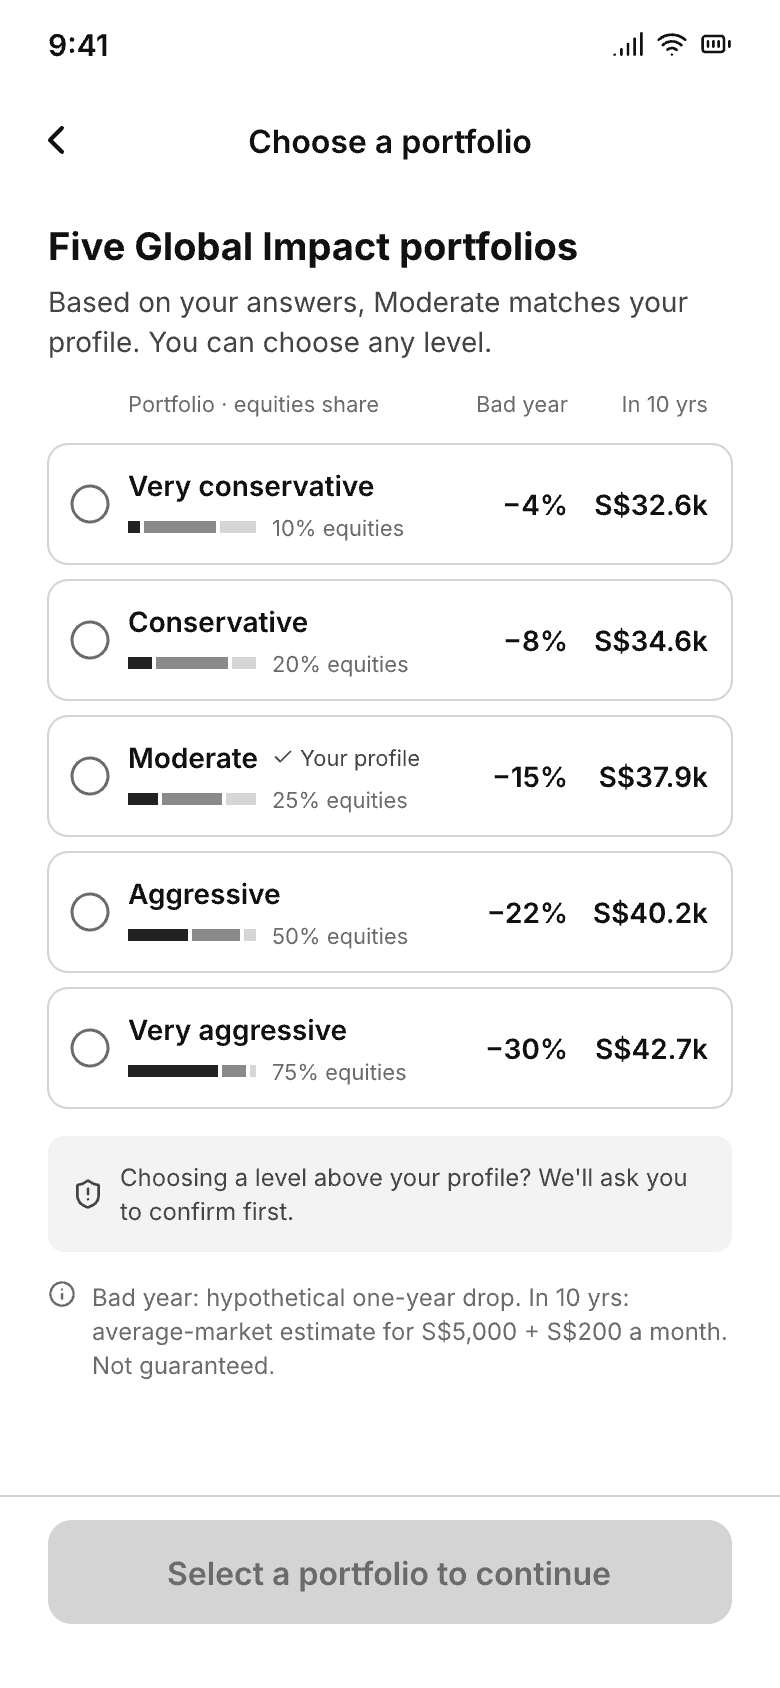
Homework for a beginner. Five portfolios and ten figures, with nothing selected, turn a recommendation into a comparison exercise.
The recommendation, whispered. A small “Your profile” tag is easy to miss in a list of equals.
A warning before a choice. Flagging above-profile picks up front reads as a telling-off before anyone has chosen. The final design only asks for confirmation once someone picks a portfolio other than the recommendation.
One more step. A button that stays disabled until you pick puts another tap between you and investing.
The same order, from sign-up to withdrawal.
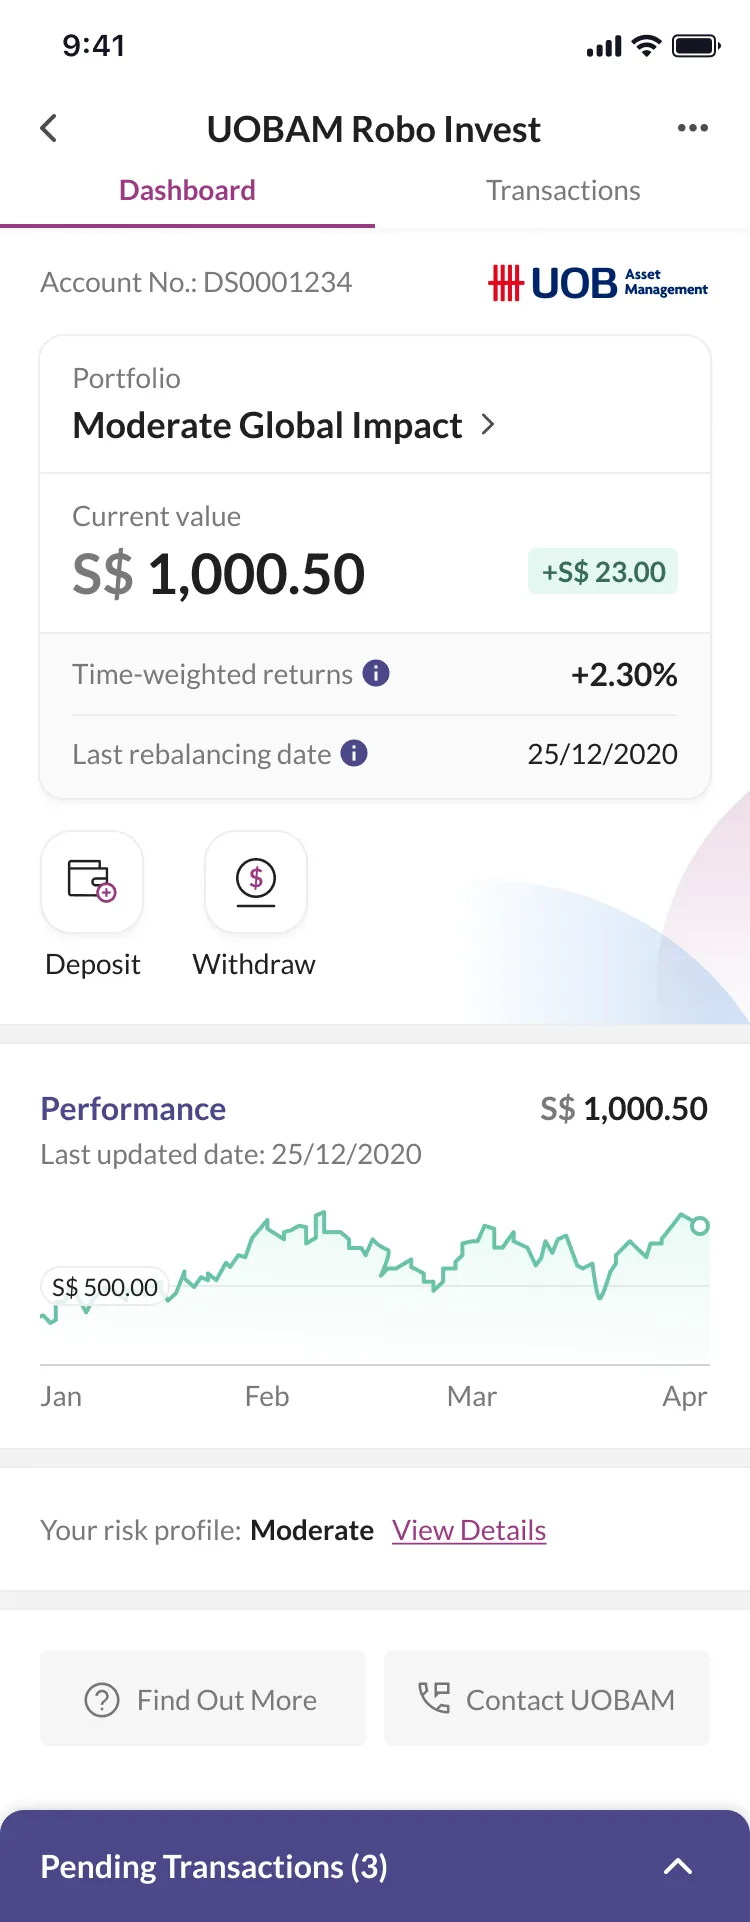
I designed the same hierarchy throughout the user journey. After the risk questions, onboarding offered one recommended portfolio with the option to change it. This limited the initial comparison while adding options if users wanted an alternative. The dashboard was designed with the investment numbers and the main actions that can be taken always visible.
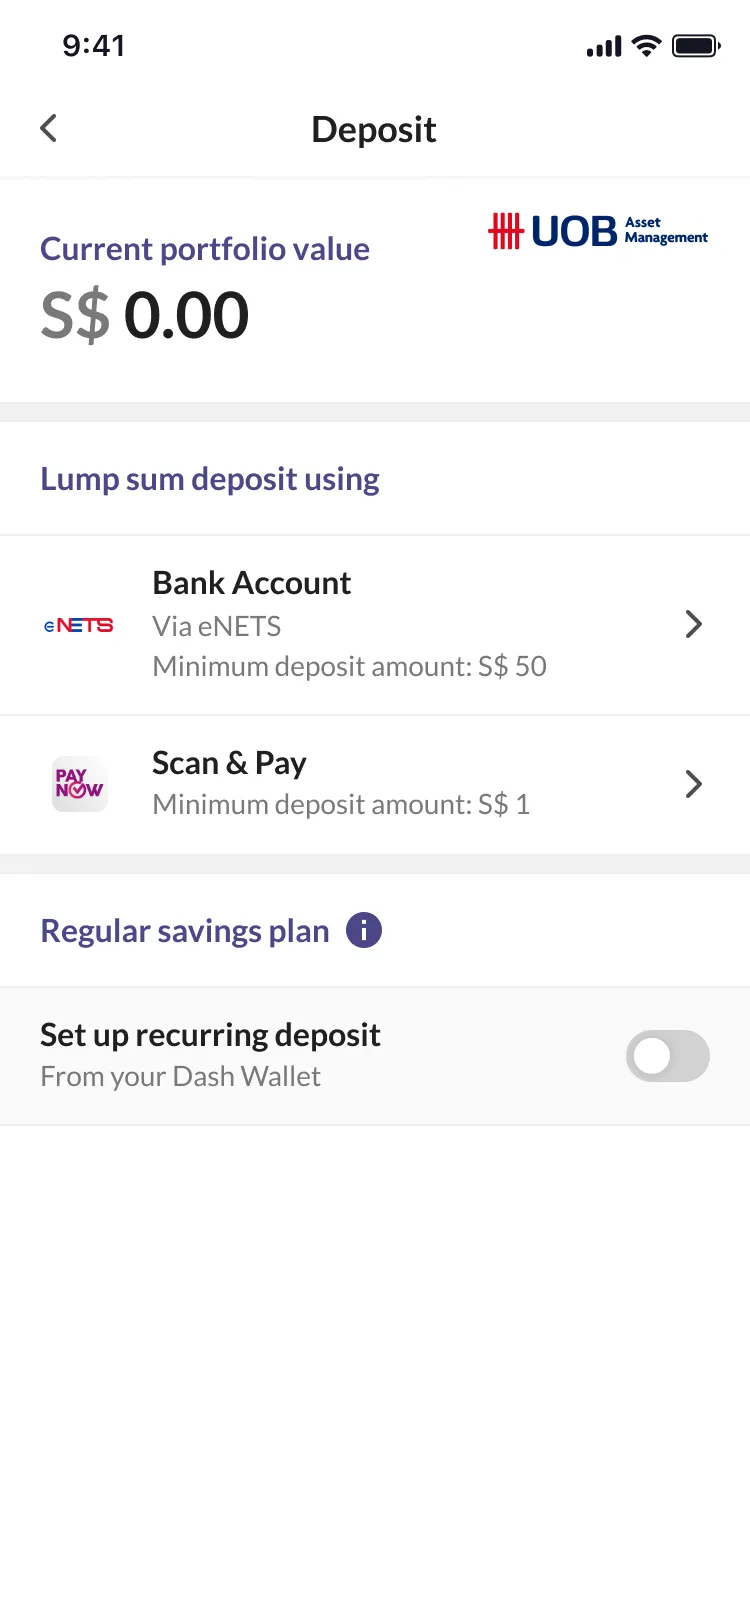
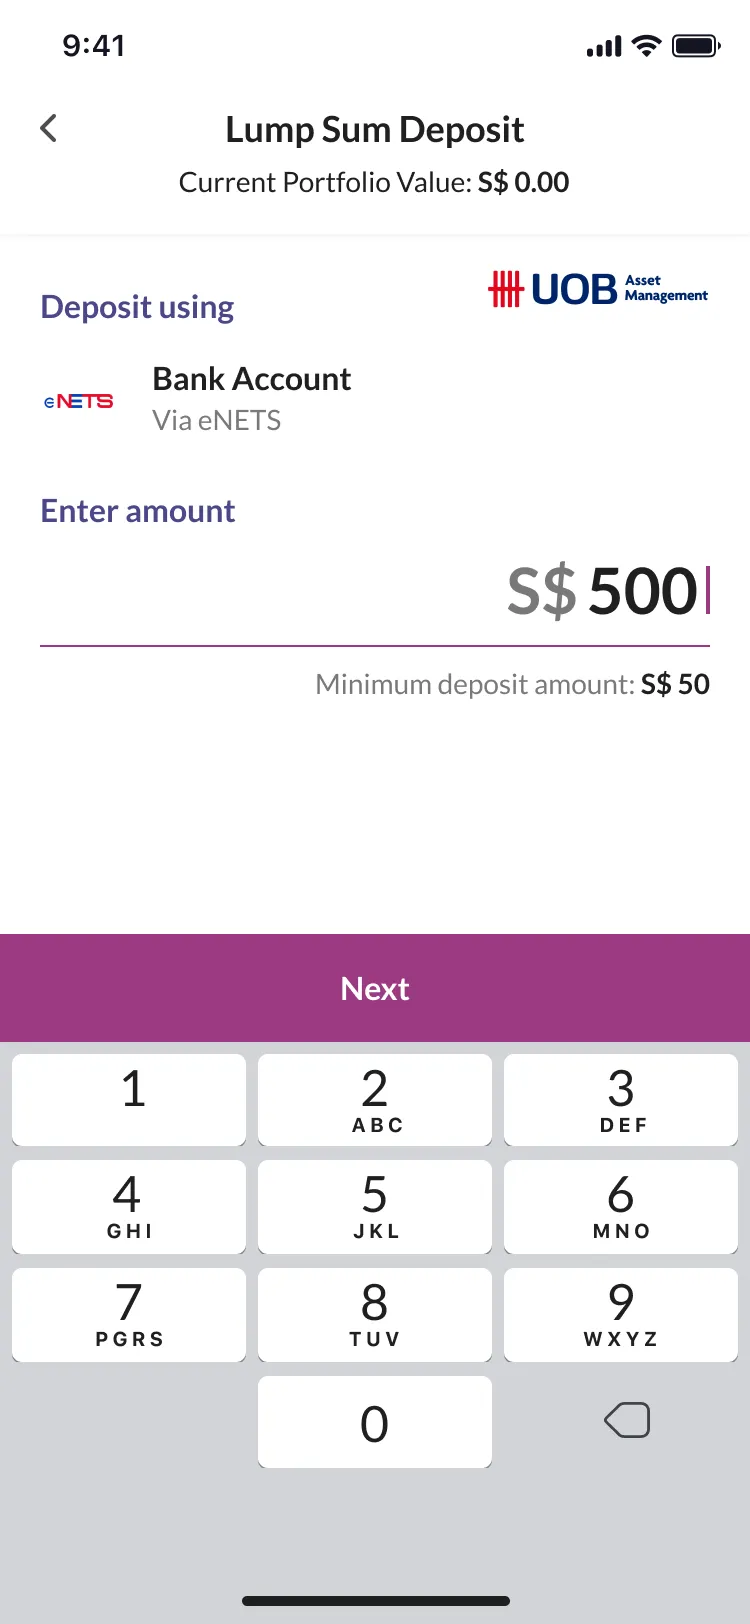
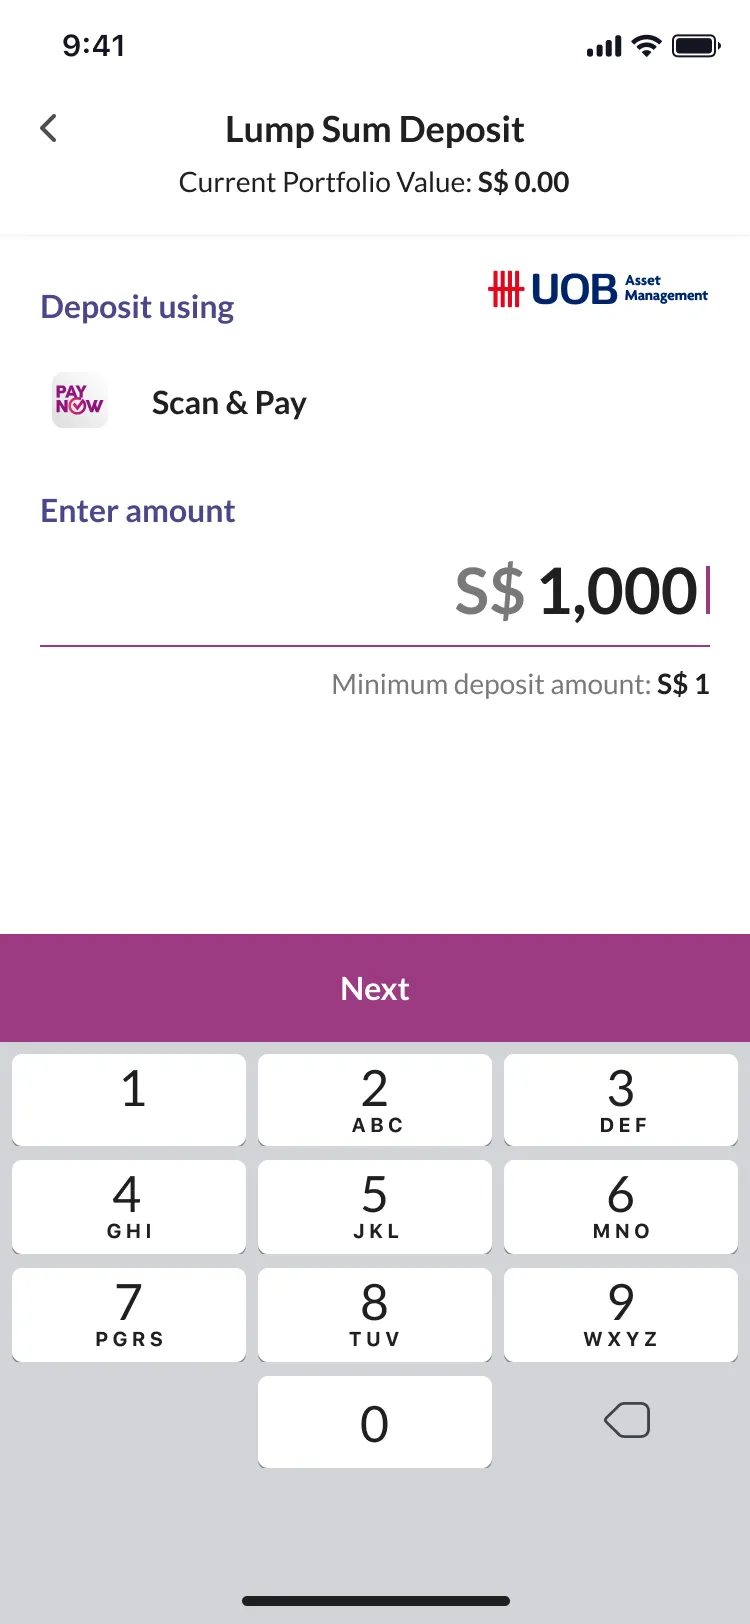
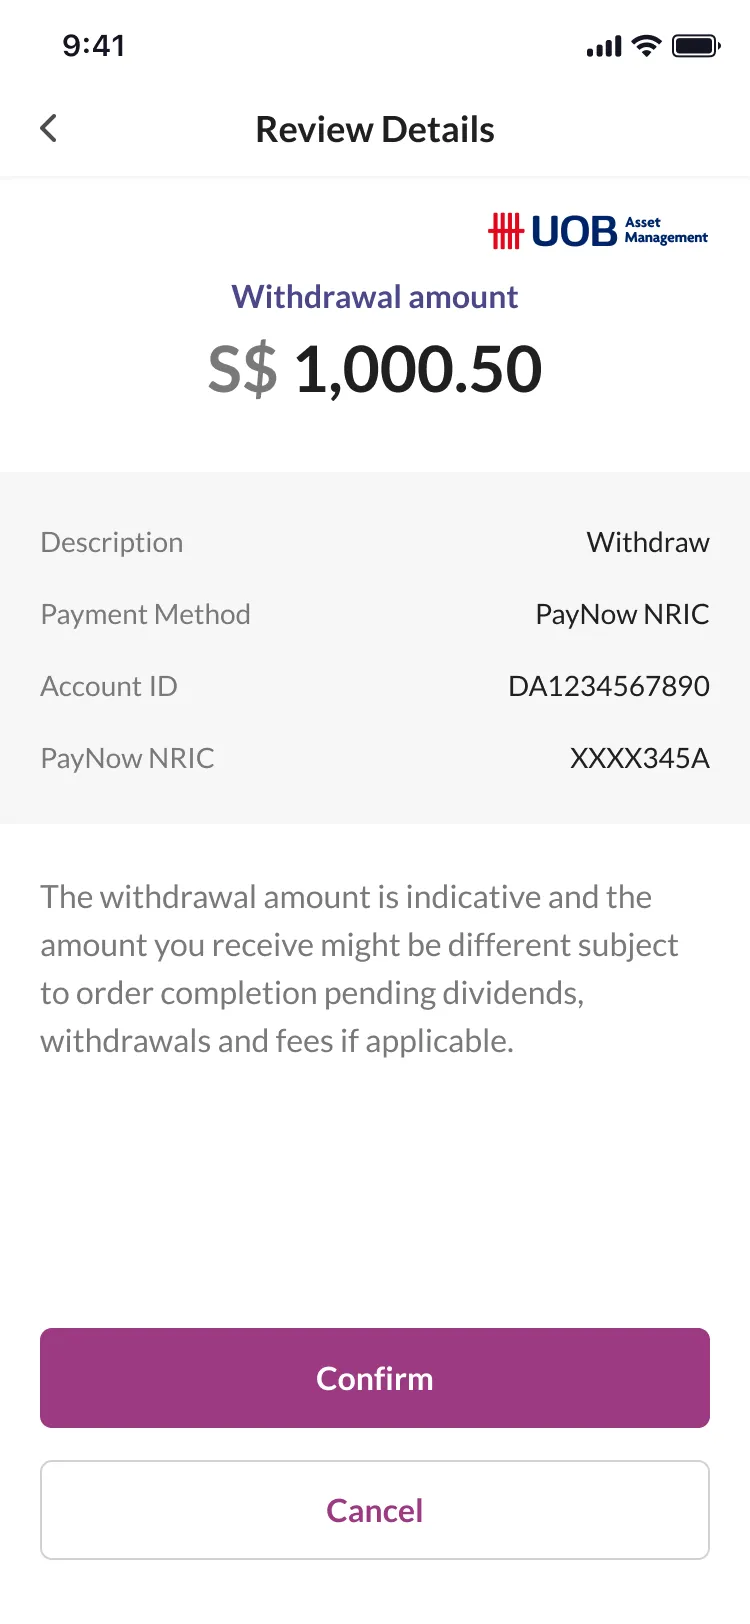
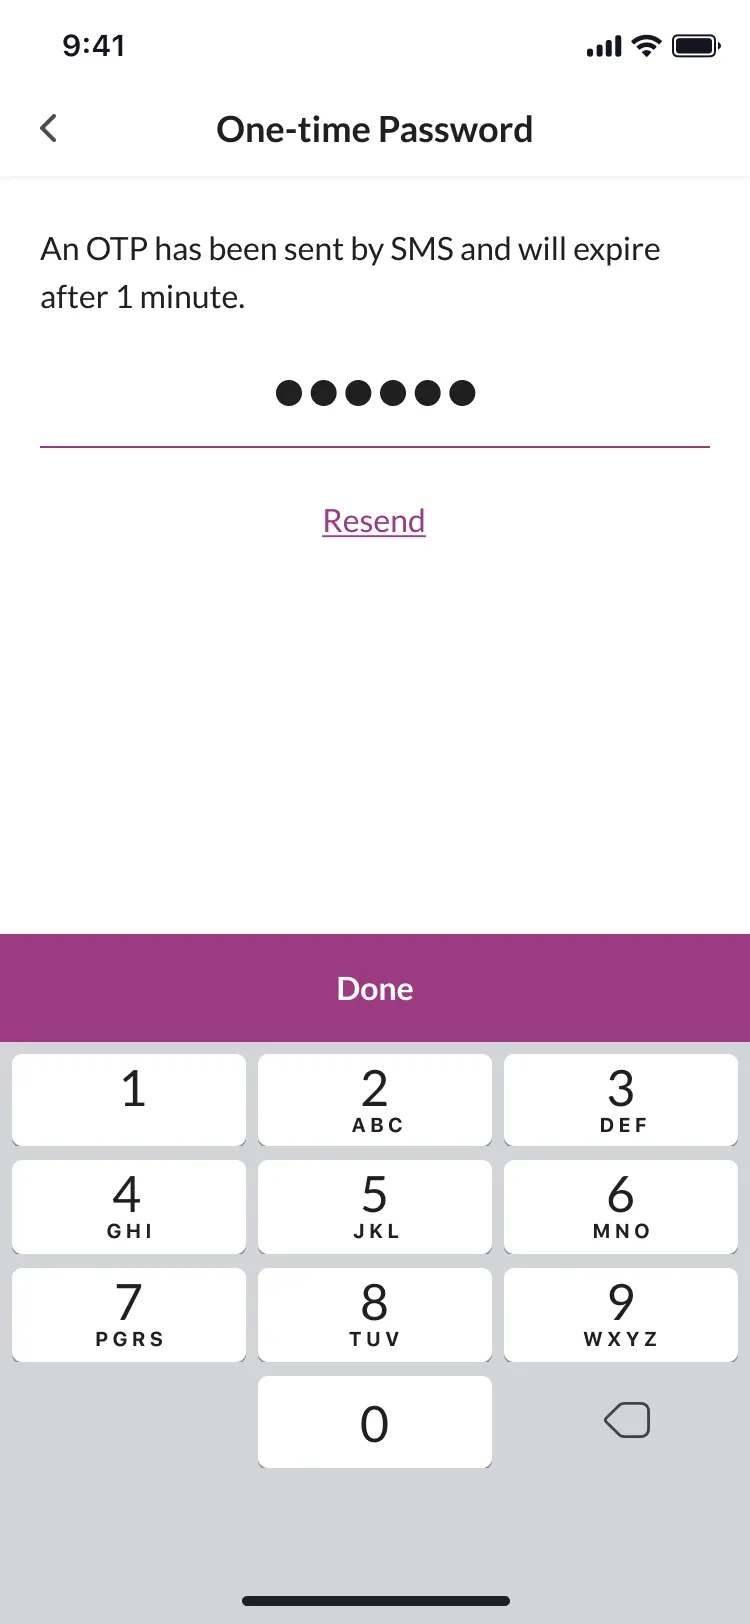
Moving money raised different questions: what the deposit options were and where users would receive their funds after withdrawal. Deposits showed each funding method’s minimum before amount entry. Withdrawals kept the destination visible, labelled the amount as indicative and allowed the user to check the details before confirmation. Those review steps were added deliberately to increase friction, giving users another opportunity to verify their intended action.
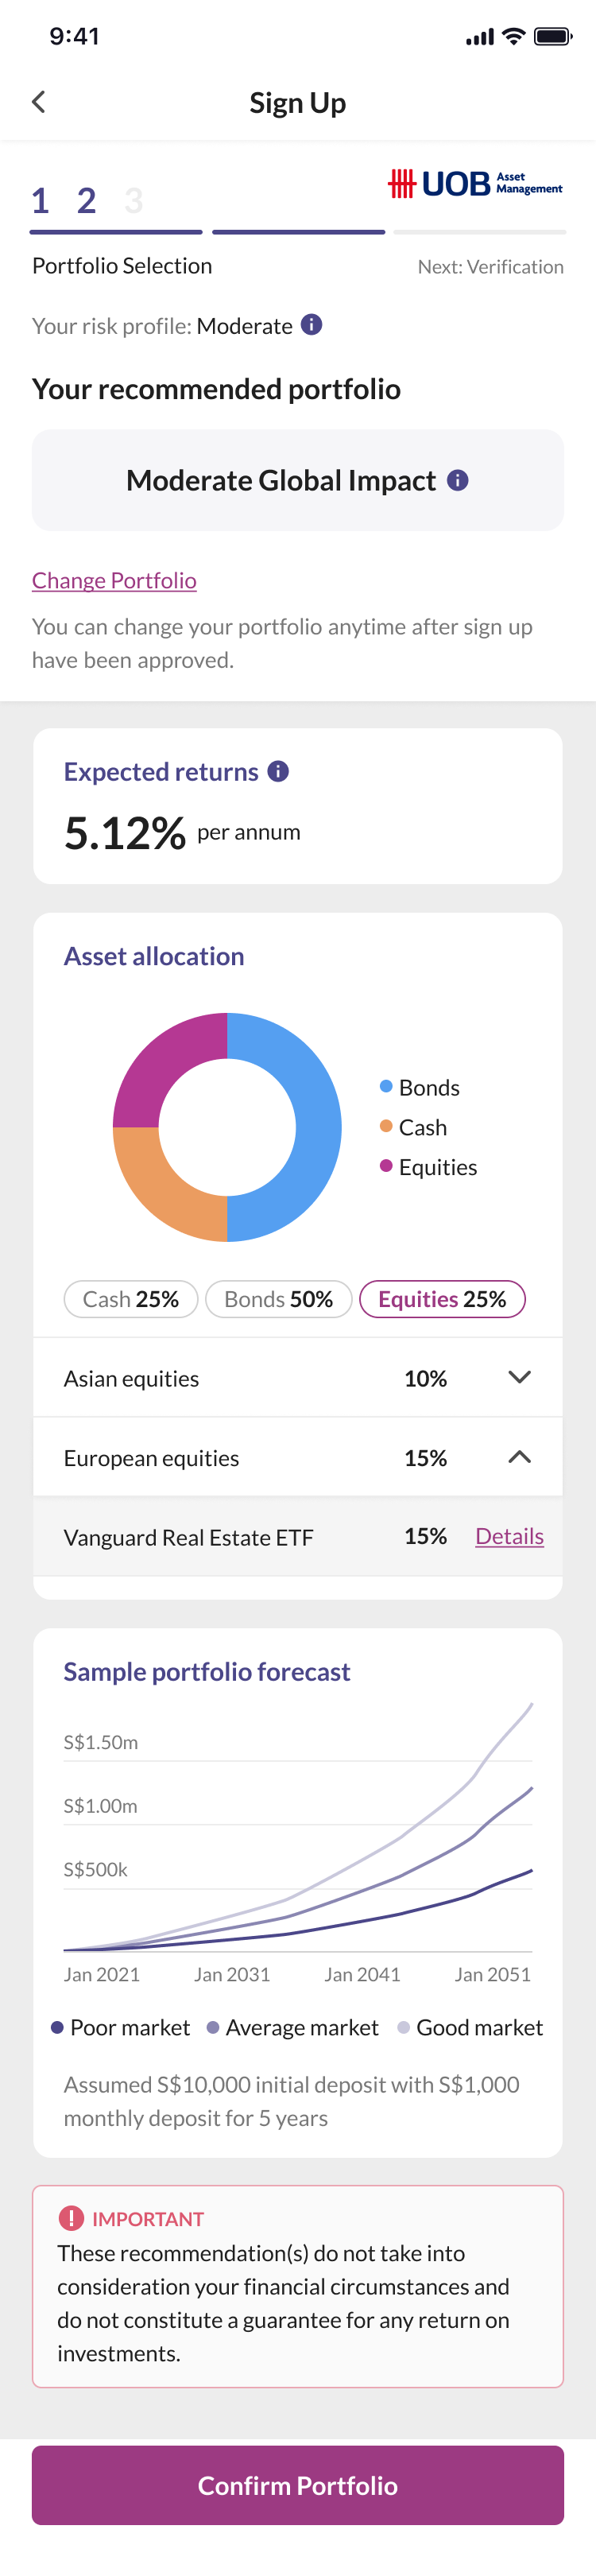
Progress at every step. A stepper shows progress on every onboarding page.
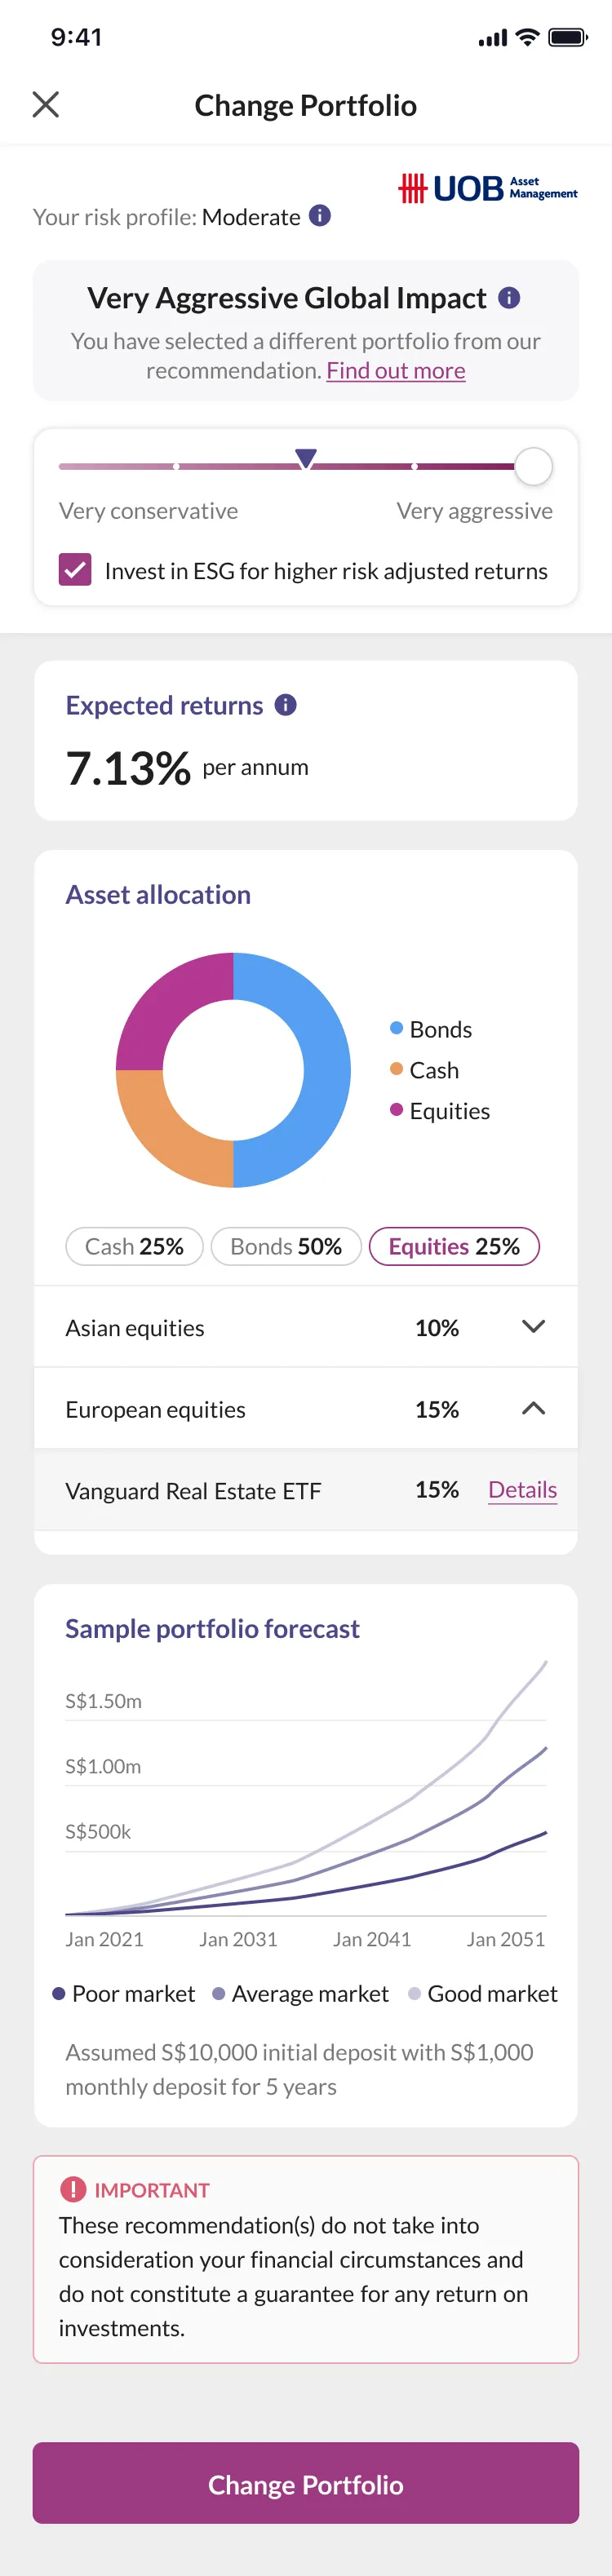
A recommendation with room to change. The risk profile provides a recommendation to start from, with the option to change the portfolio.
Explore the selected funds. Selectable chips let users explore the selected funds in more detail.
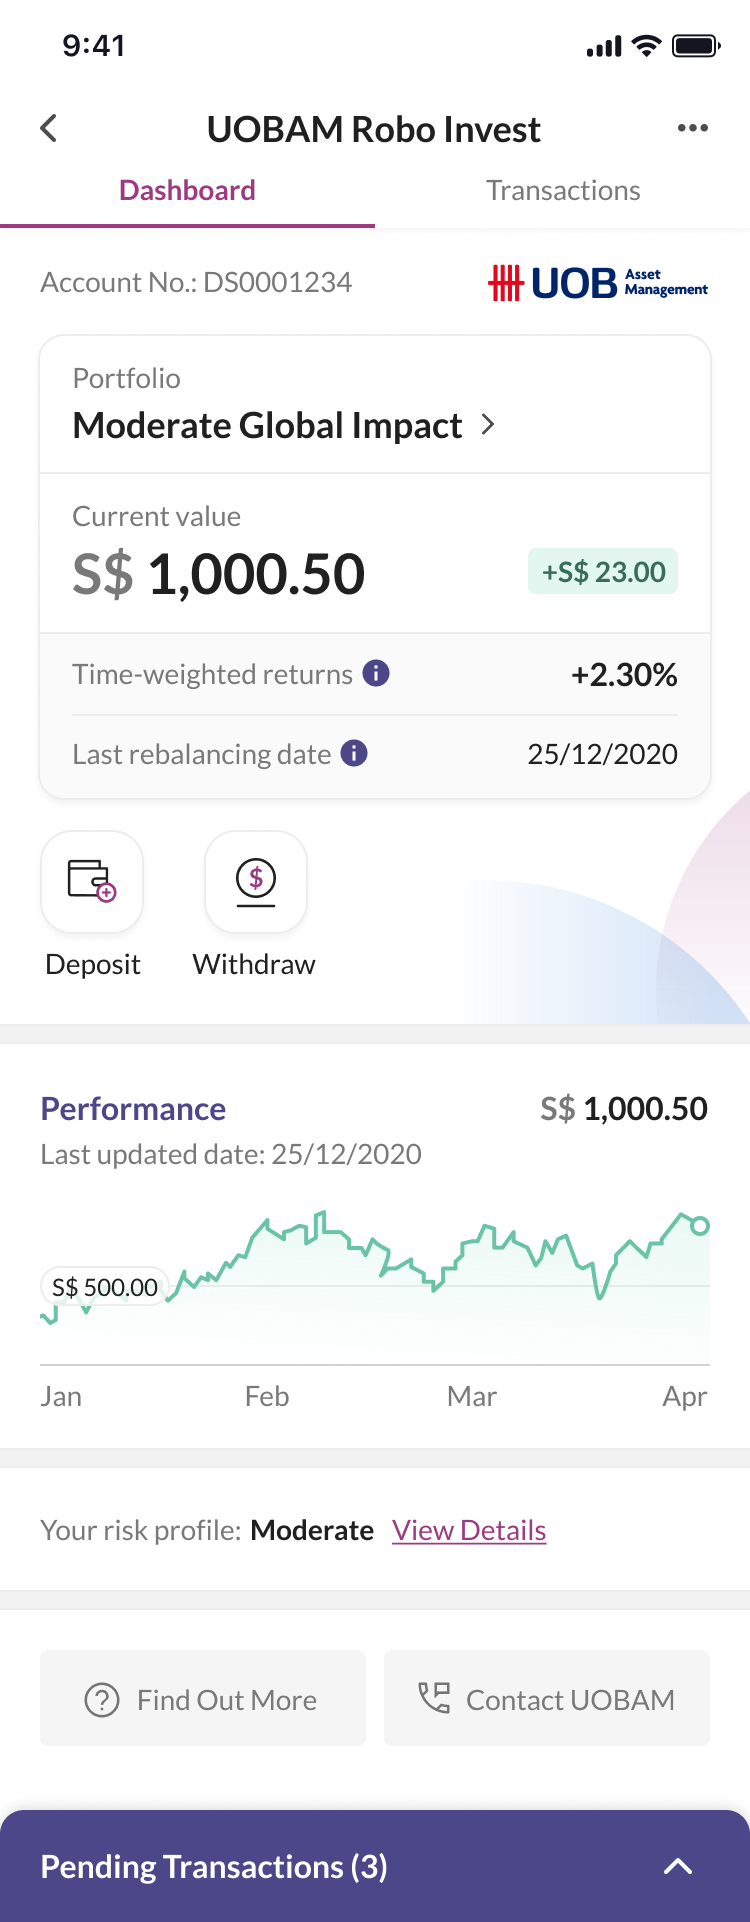
The essentials at a glance. Current value, gain and returns sit together at the top, so a balance check needs no scrolling.
Moving money, together. Deposit and Withdraw stay together so users don’t have to dig through menus.
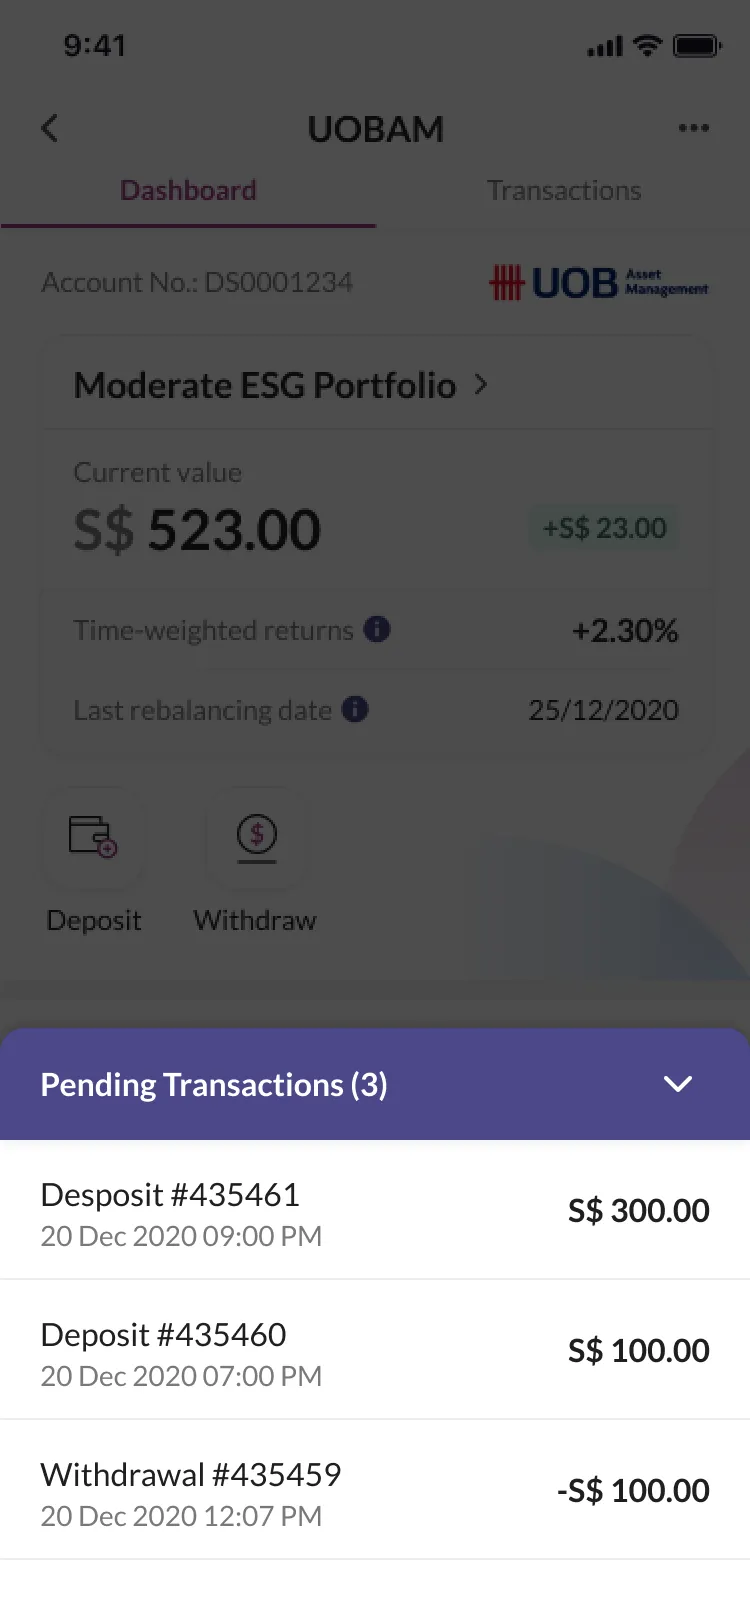
Transaction detail when needed. The pending transactions drawer keeps transaction detail out of the way until someone needs it.
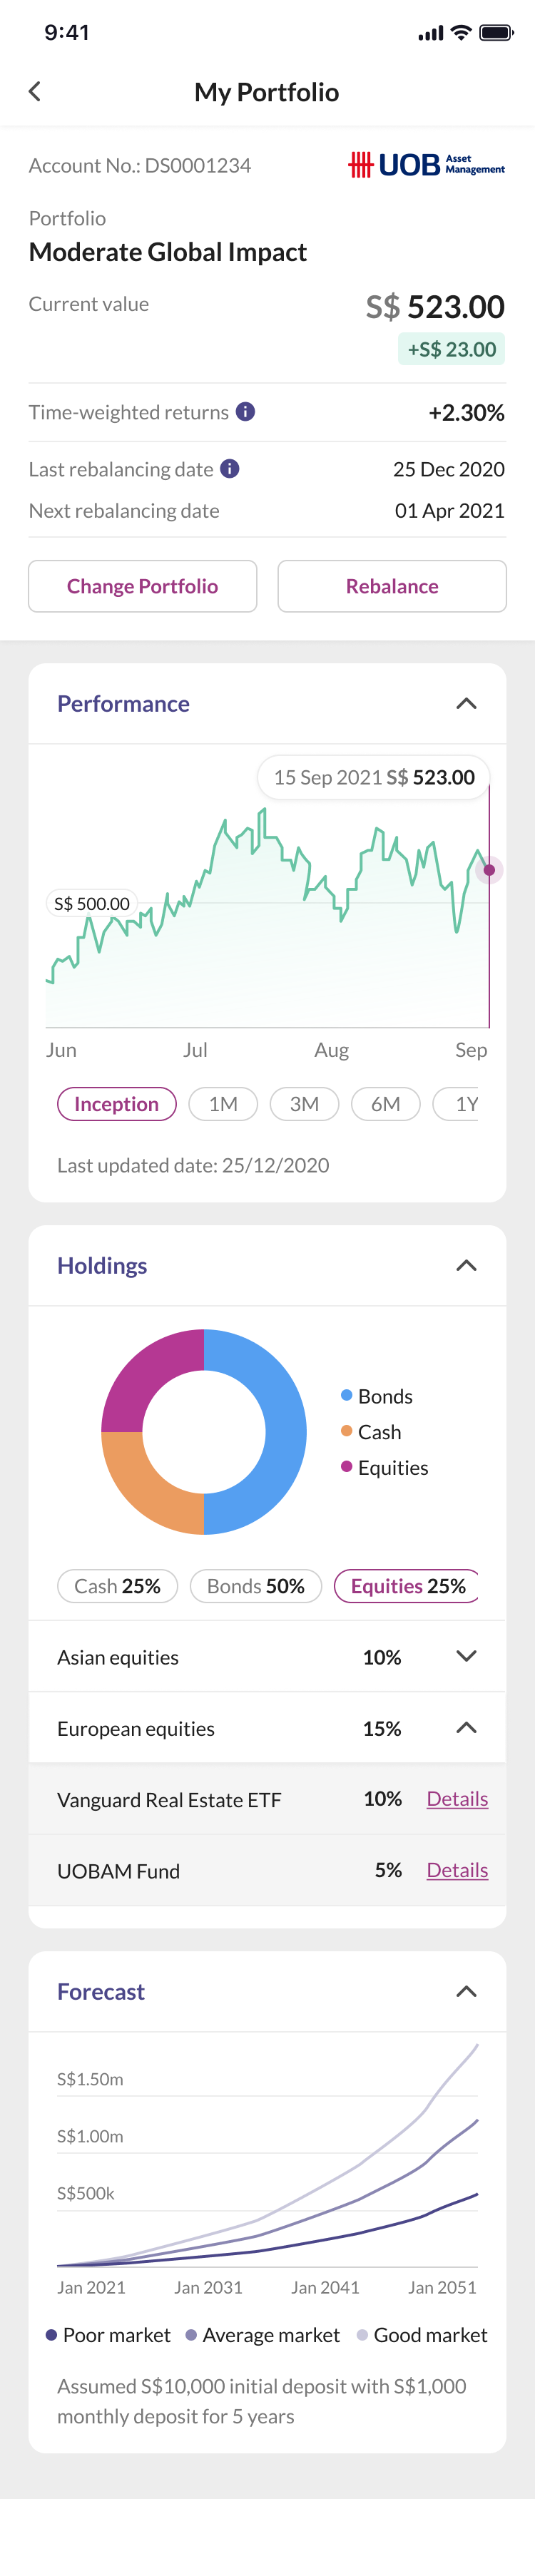
Portfolio actions within reach. Change Portfolio and Rebalance sit beside the summary.
Less information at once. Collapsible sections hide extra information that could overwhelm beginner investors.
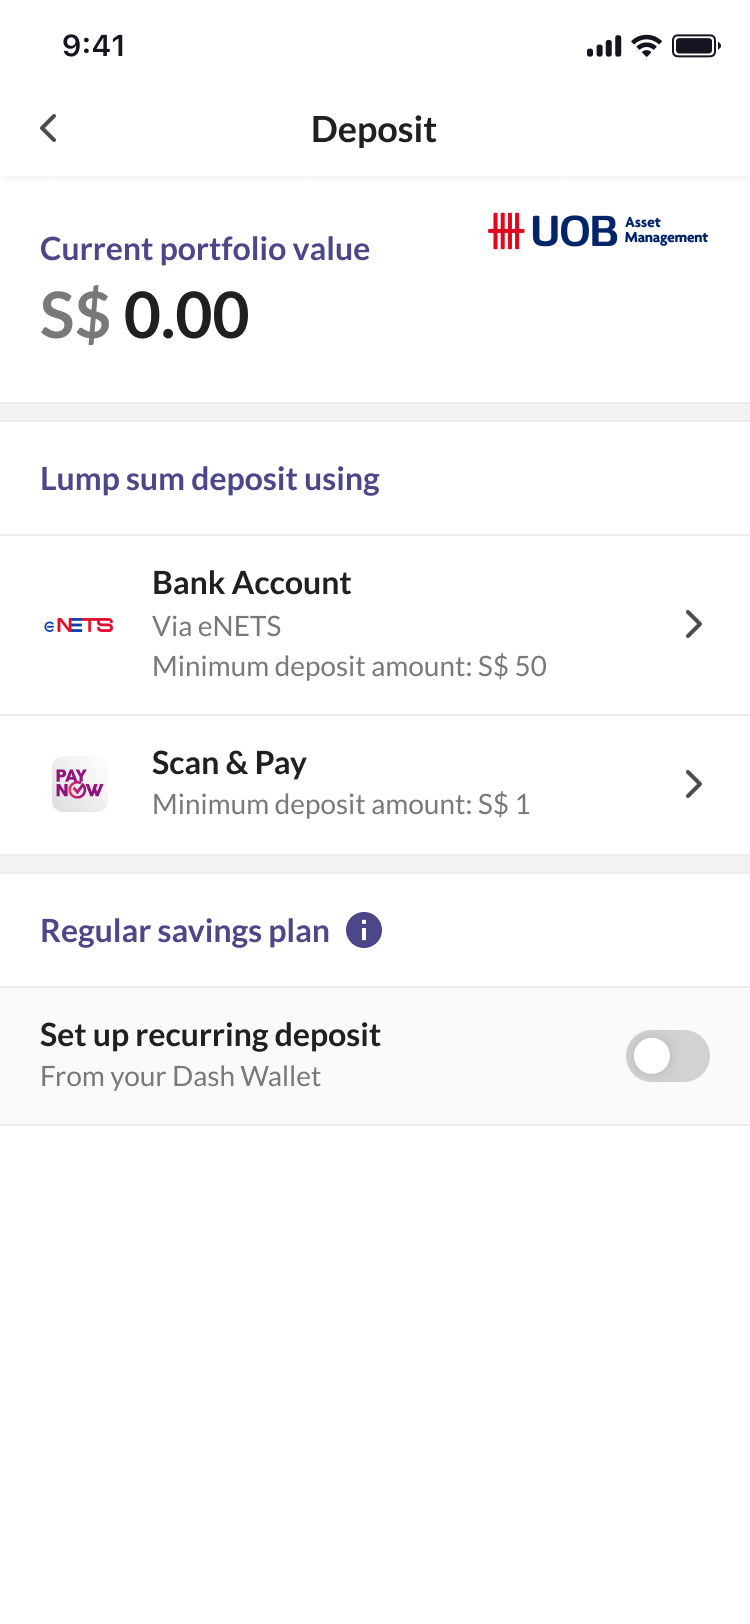
Minimum deposit amounts upfront. Each funding method clearly states its minimum before amount entry.
An ongoing action. A toggle indicates the ongoing nature of recurring deposits.
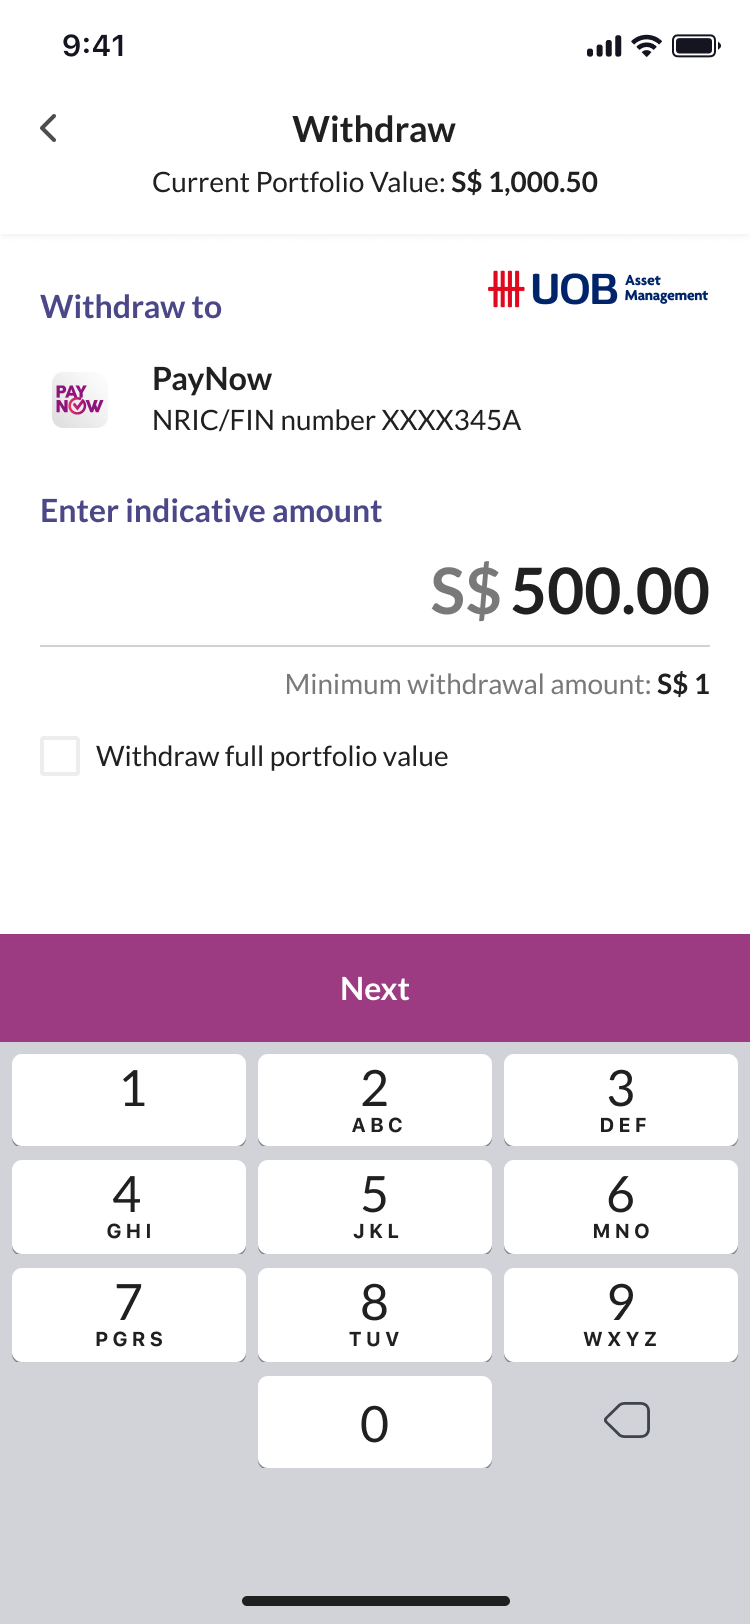
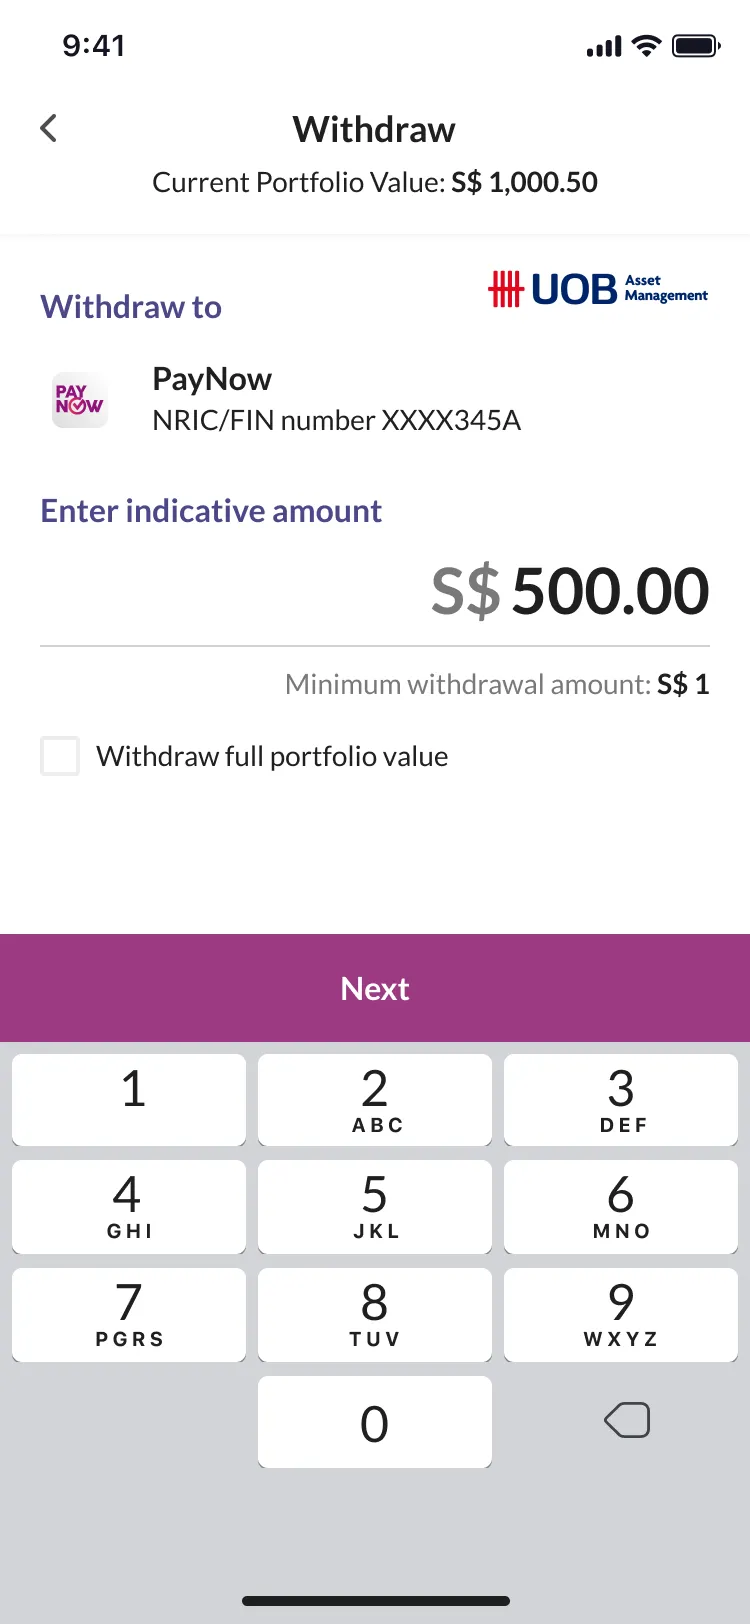
Destination and method visible. Where the money is going and the withdrawal method are always visible.
Withdraw the full amount. Users can select the full portfolio value instead of entering the amount manually.
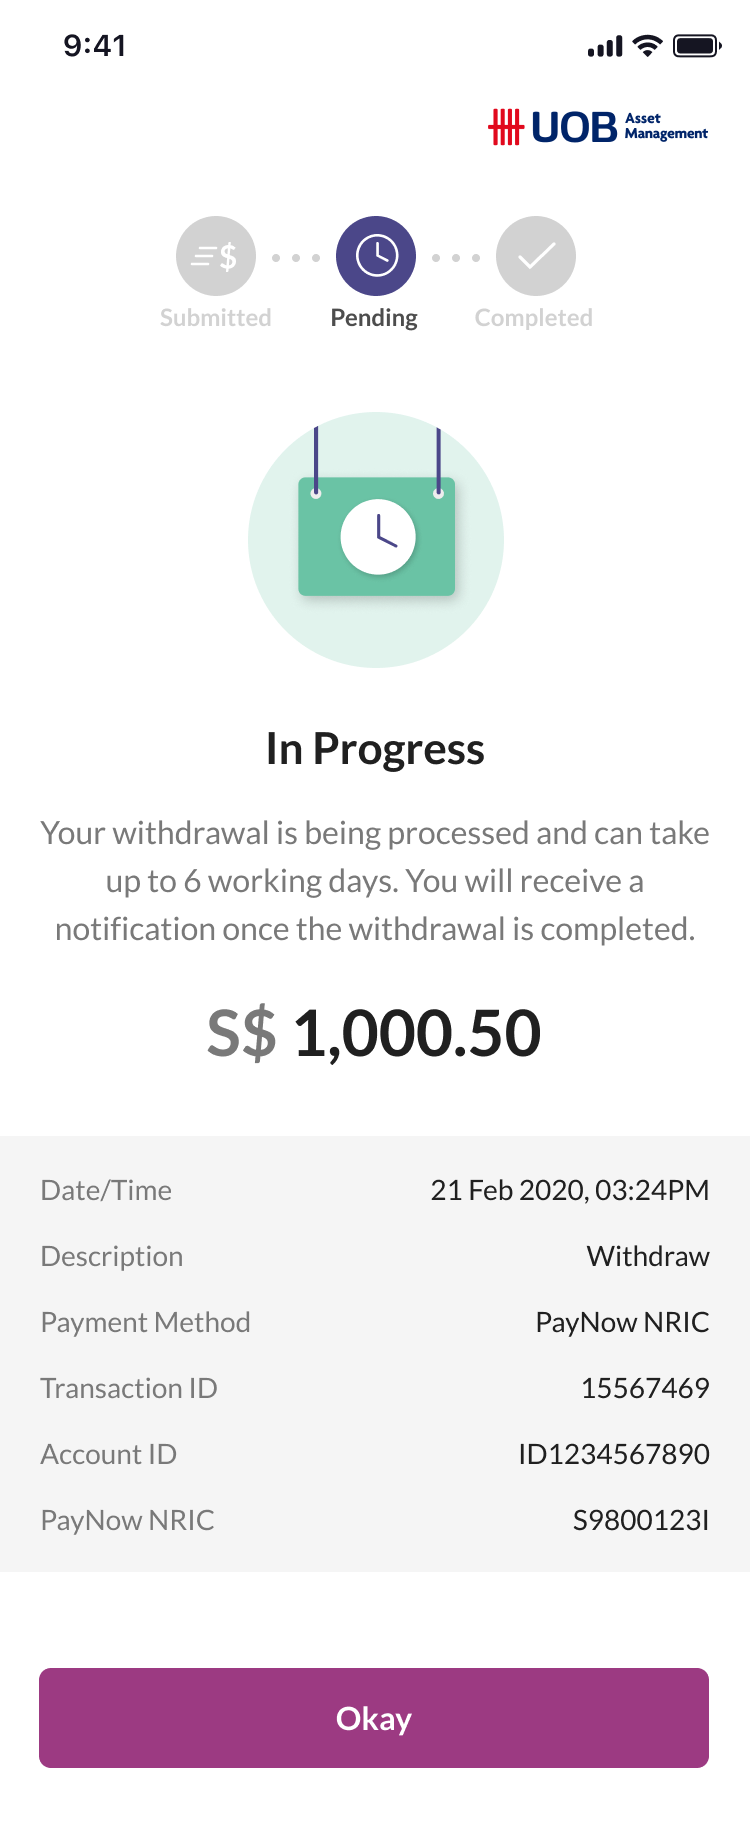
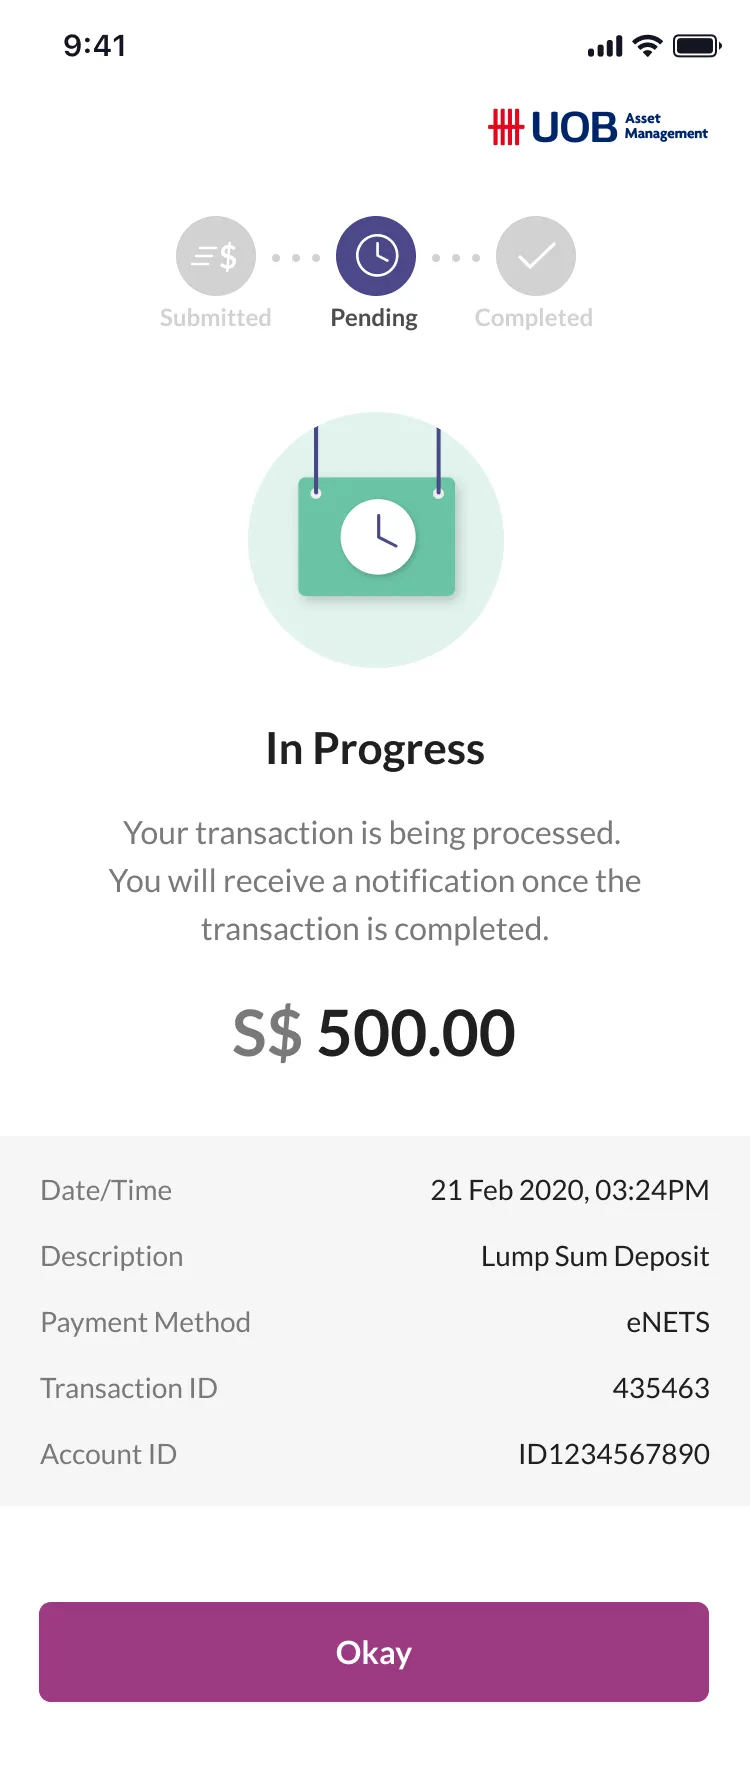
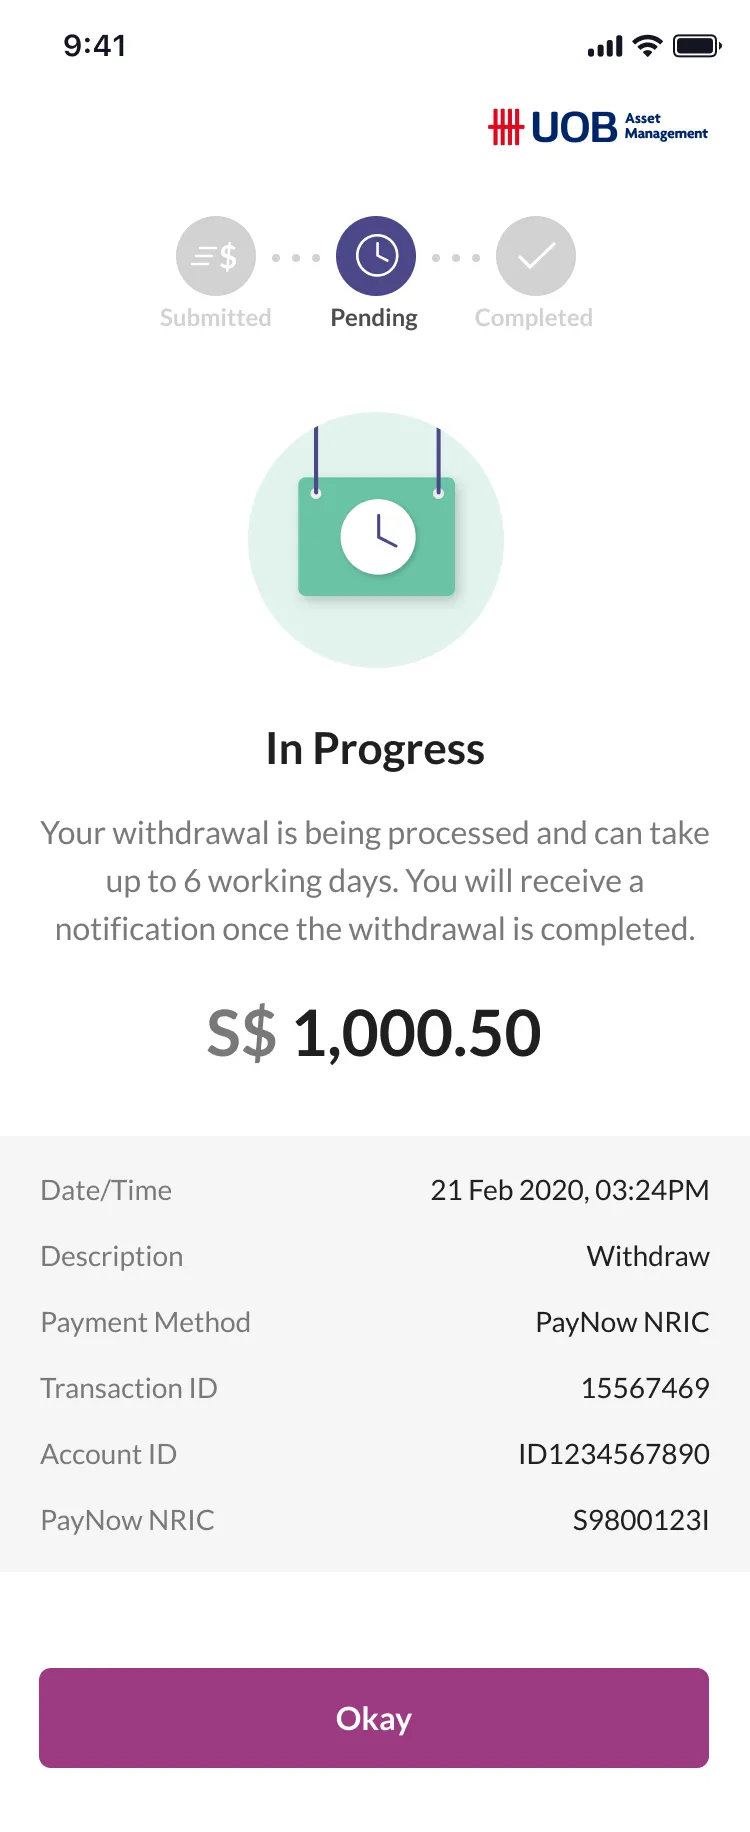
Where the money is now. A tracker shows the withdrawal moving from Submitted to Pending to Completed.
How long it will take. The screen says it can take up to 6 working days and that a notification will follow.
A record to check. The amount, payment method and transaction ID stay visible.
Build
Handing over the whole journey.
The feature followed a waterfall process, with limited iteration once designs were sent to the offshore engineering team. Wai Kean connected the Dash, UOBAM, design and engineering teams and facilitated the handoff. I didn’t work with the engineers directly, so the handoff had to answer questions before anyone asked them. It covered flows, screen states and interaction rules using Dash’s design system that the team and I co-created. My colleague June Kang owned the UI, and we worked side by side, with June leading the visual design and UI exploration. My responsibility was making the journey and its behaviour explicit.
Exceptions mattered as much to the experience as the happy path: an identity mismatch blocked progress, editing MyInfo details changed the registration route, and a withdrawal needed a review and pending state. We worked with the UOBAM team for compliance reviews and QA sign-off, and the UOBAM and Dash teams dogfooded the prototype. Those internal checks supported delivery, but we didn’t have time to test the experience with customers.
Engineering needed a few clarifications, such as whether the API had enough information to show the Performance chart in green or red for different time periods, and what I saw of the build followed the spec.
Interactive prototype
Tap through the dashboard, deposits and withdrawals on the original 2021 screens.
Explore the dashboard
Tap the portfolio name to explore performance, holdings and forecasts. Or try Deposit and Withdraw from the dashboard.
Dashboard → My Portfolio
Original 2021 screens with sample data. Payments and verification are simulated.
Enable JavaScript to try the prototype. You can scroll the dashboard preview below.
Pending Transactions (3)
Deposit #435461, 20 Dec 2020 09:00 PM, S$ 300.00. Deposit #435460, 20 Dec 2020 07:00 PM, S$ 100.00. Withdrawal #435459, 20 Dec 2020 12:07 PM, -S$ 100.00.
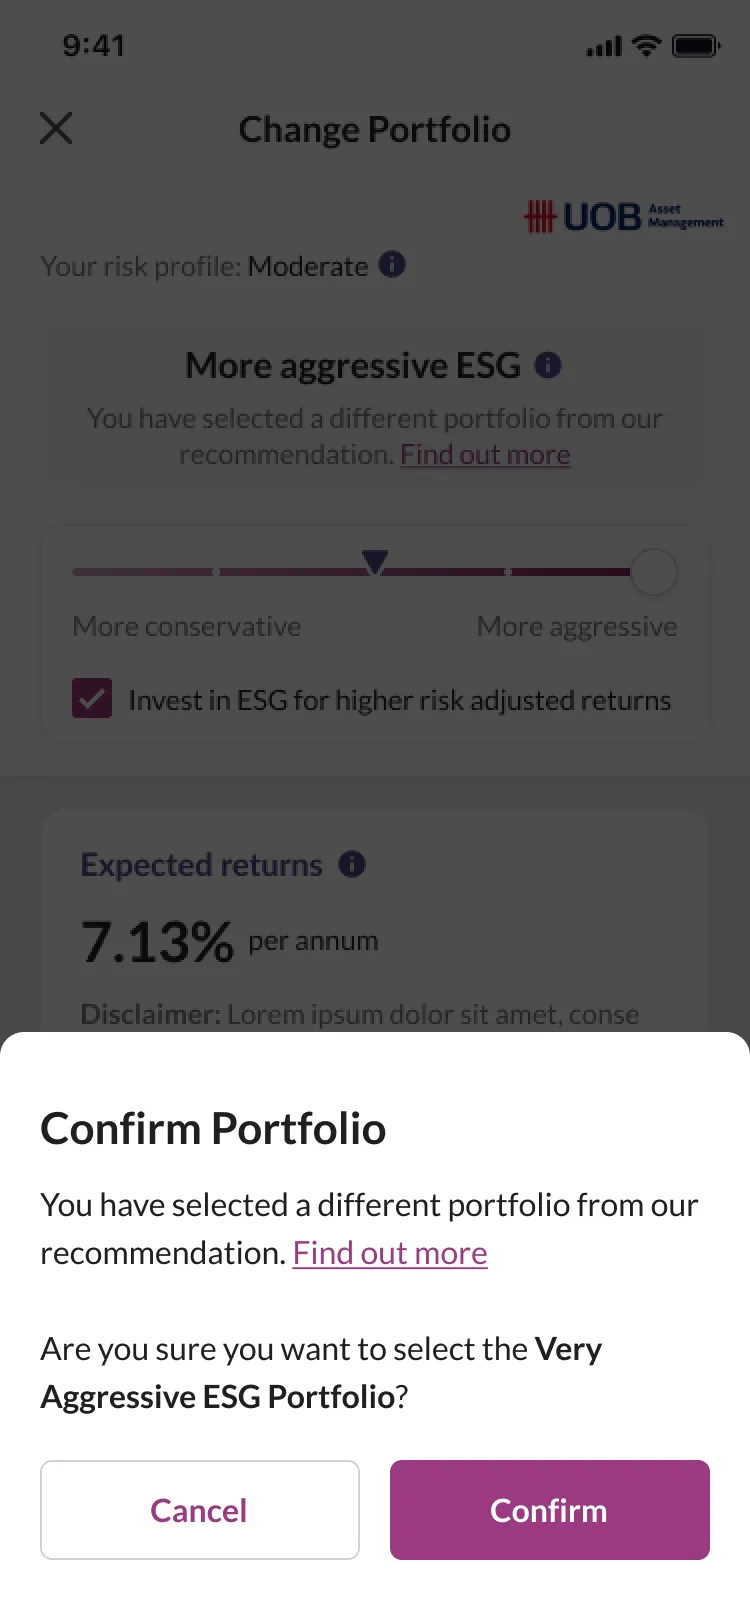
Confirm Portfolio
You have selected a different portfolio from our recommendation. Find out more. Are you sure you want to select the Very Aggressive ESG Portfolio?
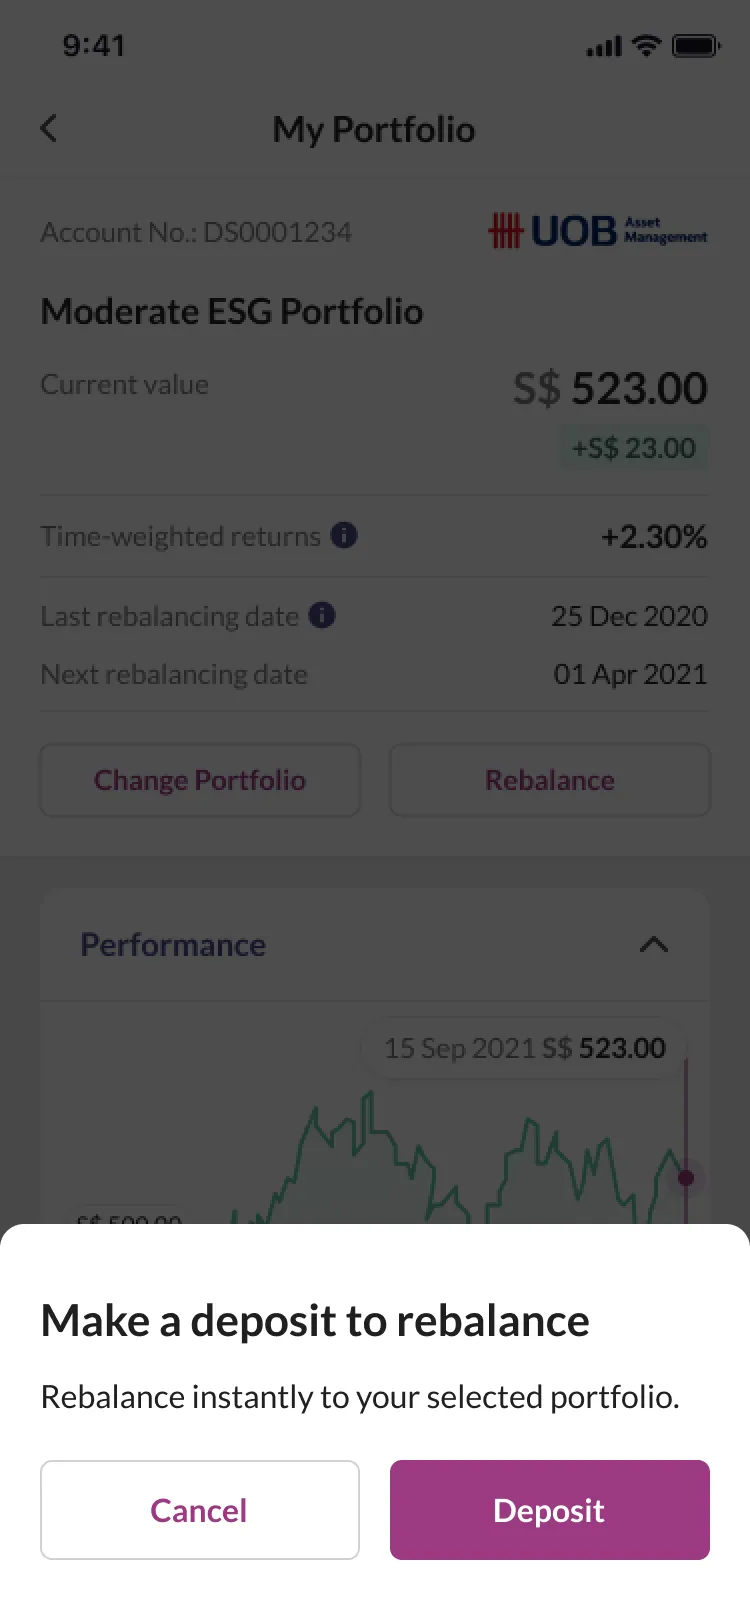
Make a deposit to rebalance
Rebalance instantly to your selected portfolio.
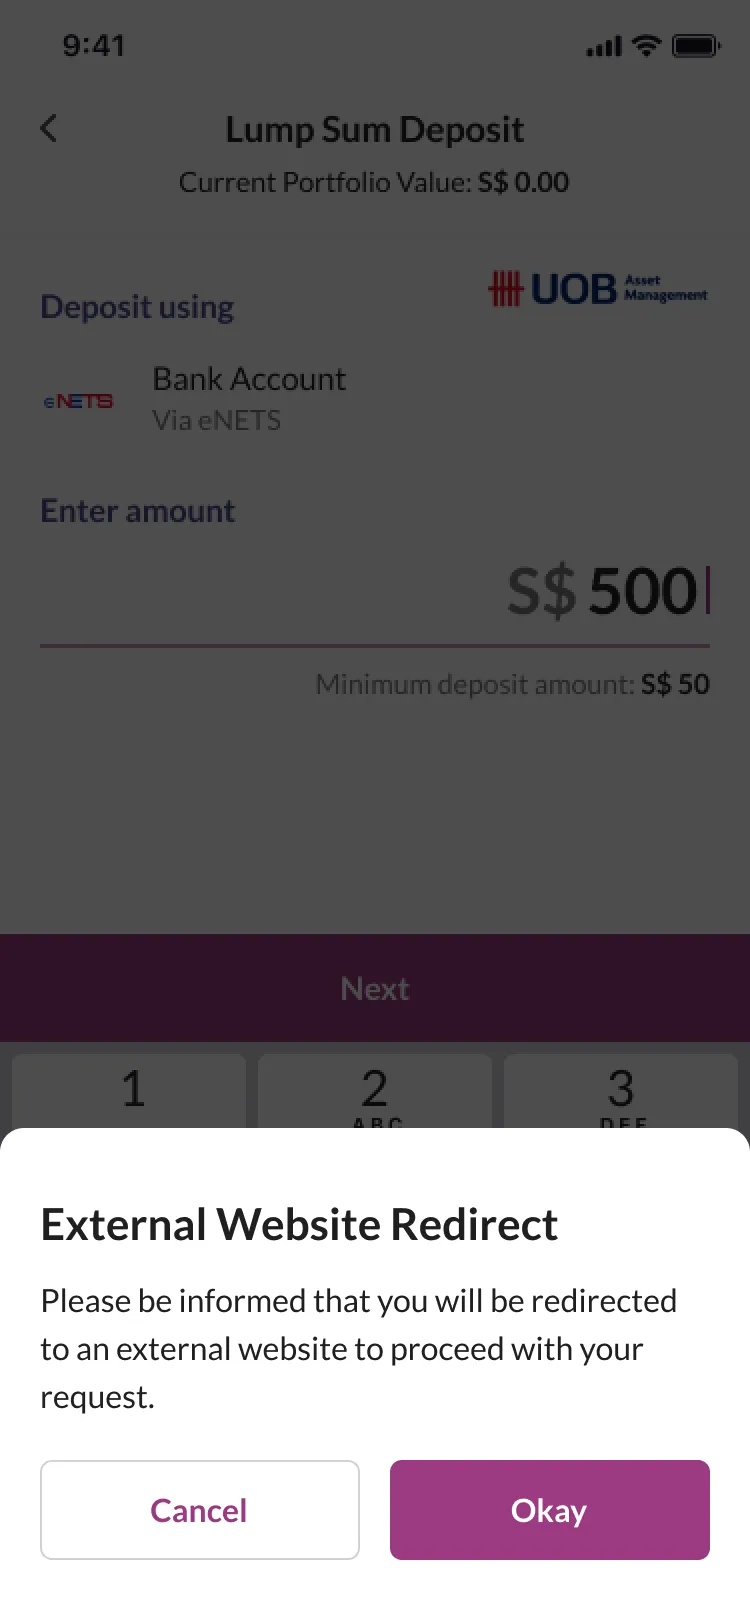
External Website Redirect
Please be informed that you will be redirected to an external website to proceed with your request.
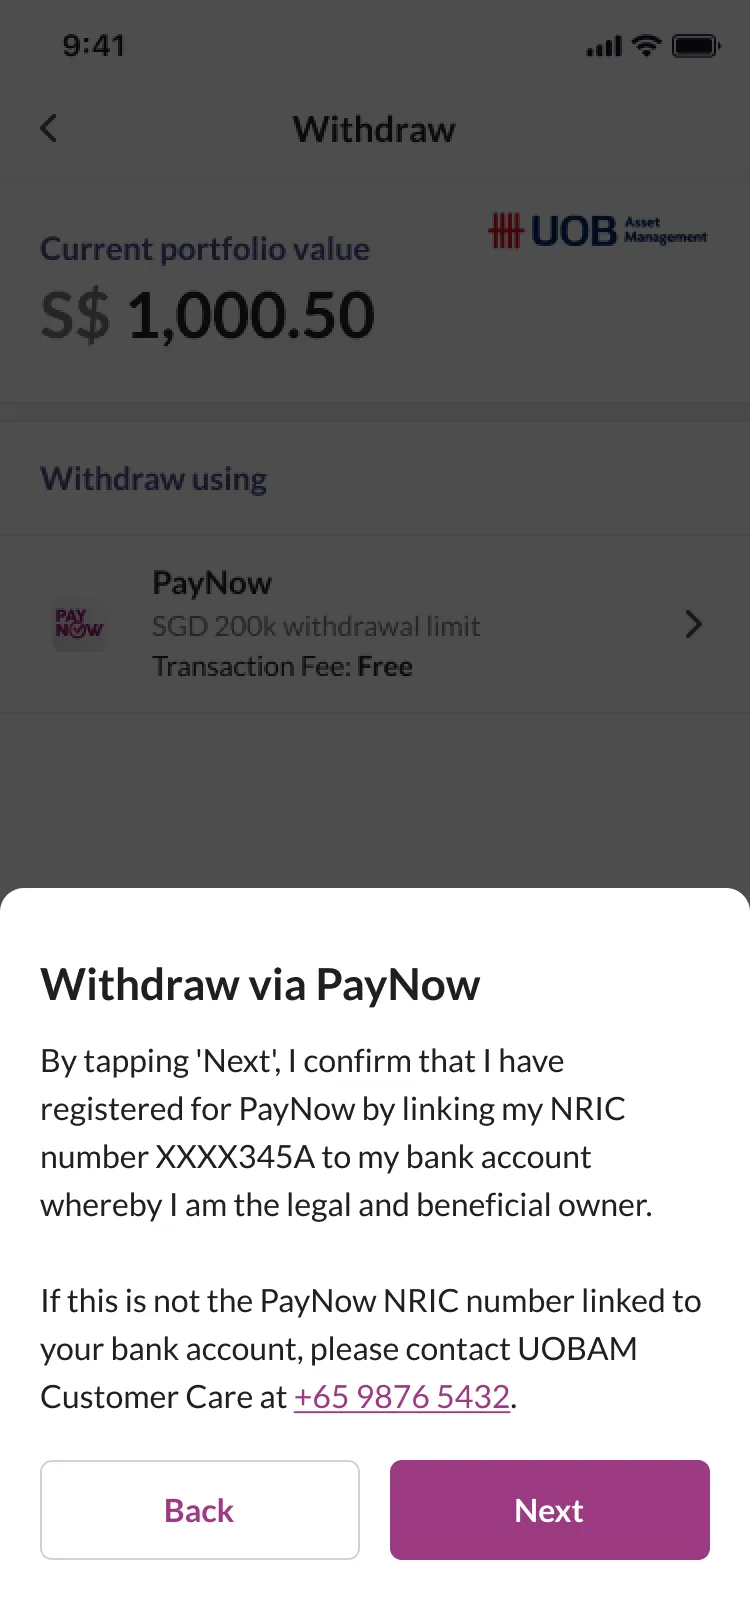
Withdraw via PayNow
By tapping Next, I confirm that I have registered for PayNow by linking my NRIC number XXXX345A to my bank account whereby I am the legal and beneficial owner. If this is not the PayNow NRIC number linked to your bank account, please contact UOB AM Customer Care at +65 9999 9999.
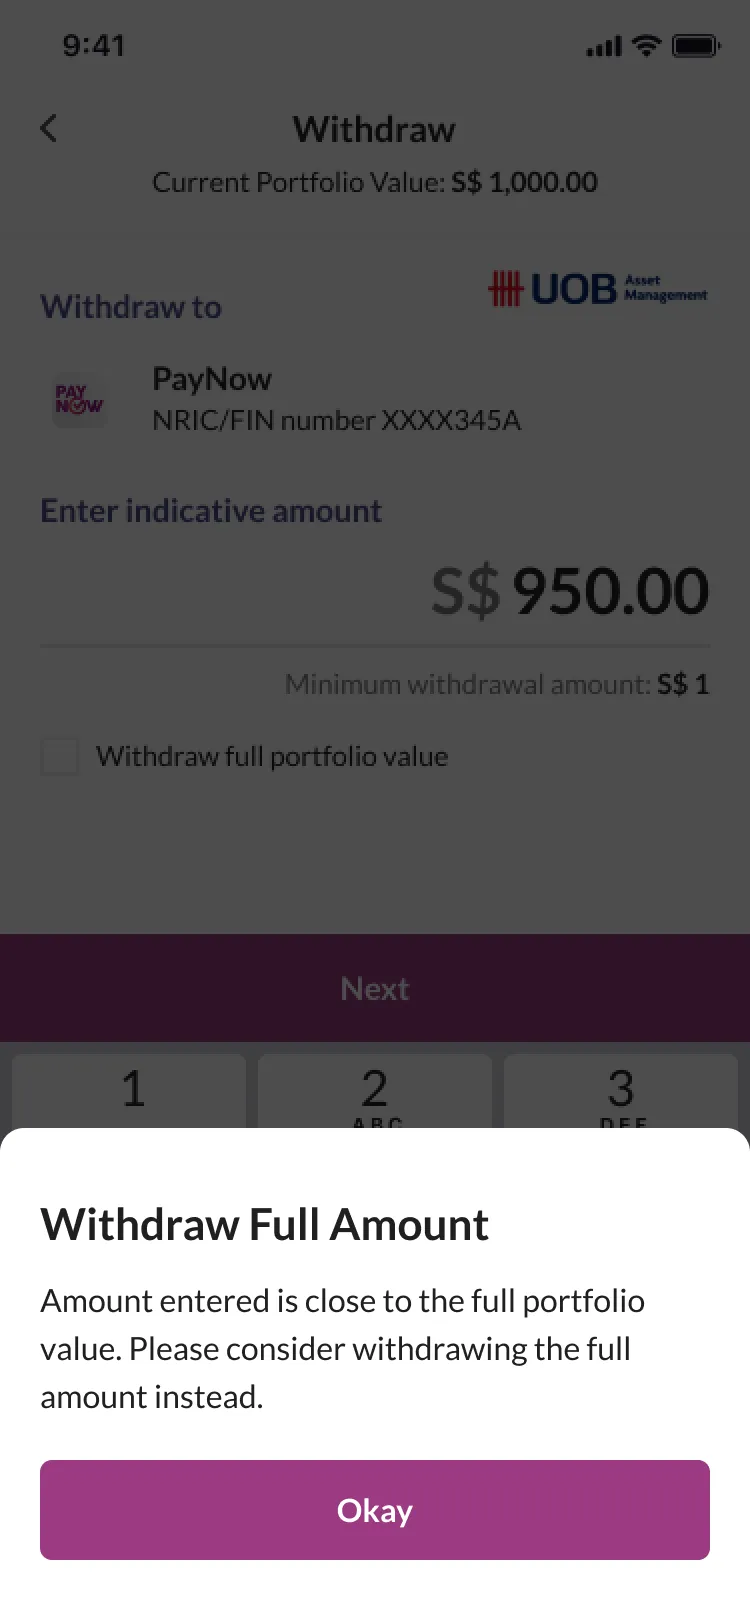
Withdraw Full Amount
Amount entered is close to the full portfolio value. Please consider withdrawing the full amount instead.
Regular savings plan
Set up a recurring deposit from your Dash Wallet. The handoff supports weekly or monthly deposits, with a minimum of S$50.
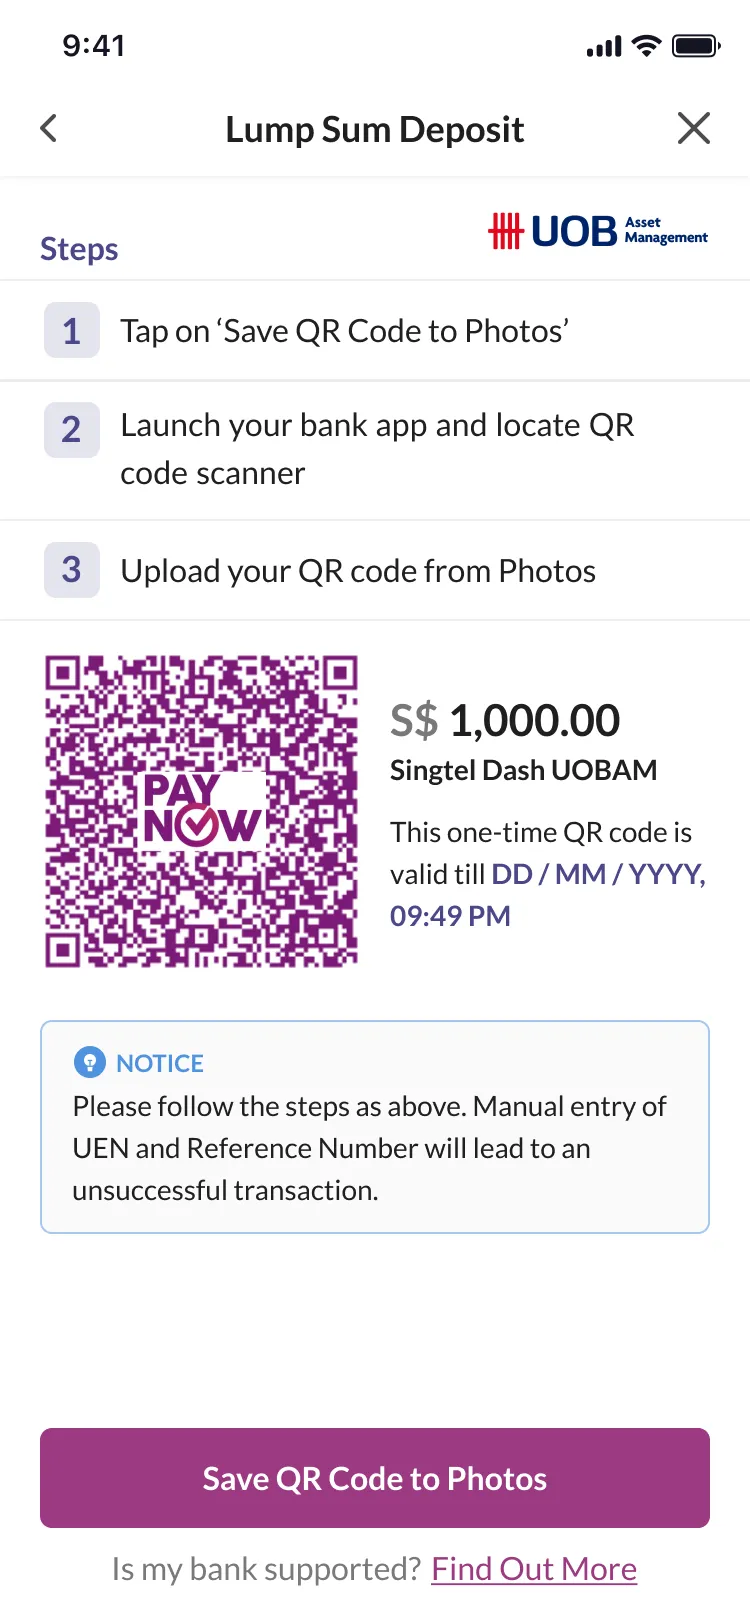
Scan & Pay
In the live app, this button saves the QR code to Photos so you can upload it in your bank app. Payments are simulated in this preview.
iPhone 11 Pro · 375 × 812 px
Dashboard
Launch
Launched in December 2021.
Singtel and UOBAM announced Robo-Invest’s launch on 21 December 2021.
I left around the middle of 2021, while the offshore team was still developing it, so I have no adoption figures. What I can point to is what the design changed before handover:
- Commitment moved earlier. The handoff moved the first risk question from step 12 to the start of onboarding, so someone who can’t invest finds out before handing over personal details.
- A clear handoff. Engineering needed a few clarifications, and what I saw of the build followed the spec.
- A system that spread. All newly introduced features used the design system, which then spread bit by bit through the existing app.
Even with the same deadline.
- Share from ideation. I used to wait until everything was complete before sharing with the team, but that just slowed things down. Now I share from the ideation stage.
- Hand over a way to measure. I’d define the funnel from risk questions to submitted identity details to first deposit, so the drop-offs would show where to iterate after launch.
With more time.
- Test the risk questions. I’d run guerrilla tests of the prototype with people new to investing, on the wording and on where the “no risk” answer sits.
- Check comprehension. I’d check whether people understand their holdings, and the difference between past performance and a forecast.